Car Loan Interest Calculator
Dealers quote you a monthly payment. Nobody quotes you the interest — and at bad-credit rates, the interest is a second car payment hiding inside the first one. Put your numbers in and see the whole cost, year by year, before you sign anything.
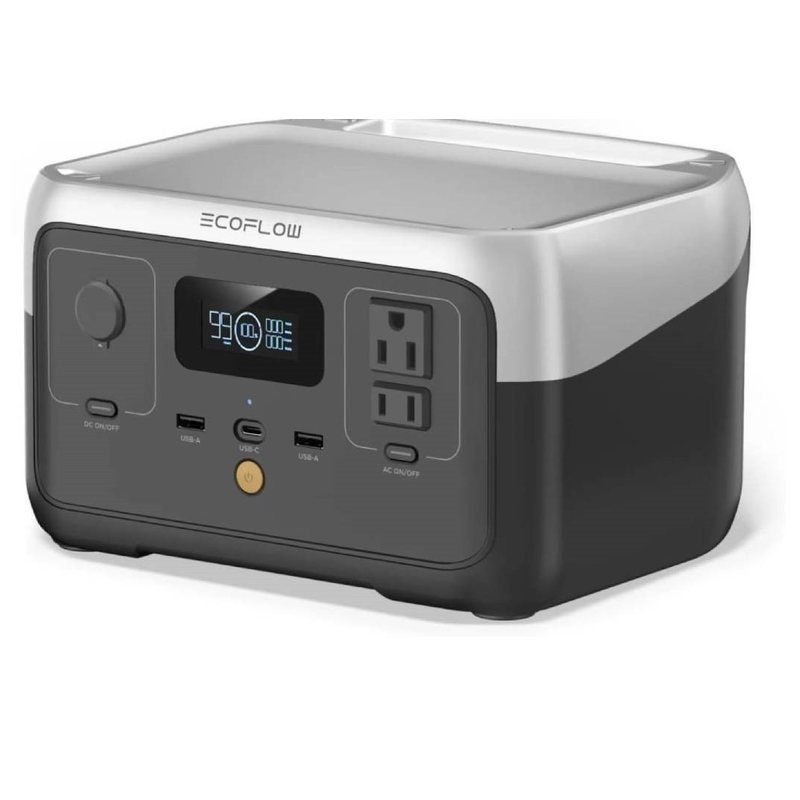
Interest this size means the car has to last. This keeps a phone, lights, and a small fridge running when the power drops, so one bad night does not become a missed shift.
$186.29 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.

You are paying enough for this car already. Keep it watched where it parks at night for one flat price, no wiring and no monthly fee.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Interest by year — watch it shrink
Your rate depends on your score — the presets are Experian Q2 2026 averages.

A locked shed takes the tools and gear out of the trunk and garage, so the car you are paying on stays clean, dry, and worth more.
$137.21 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
The interest is a second car payment hiding inside the first
Here is the number nobody at the dealership will say out loud. Borrow $15,000 at the subprime average of 19.10% over 60 months and the interest alone comes to $8,396. That is more than half the price of the car, paid a second time, quietly, a slice out of every payment. Spread out, it is about $140 a month that buys you nothing but the loan itself. At 19 to 21 percent, you are not making one car payment. You are making two, and only one of them comes with a car.
It gets heavier at the start, too. Interest is charged on your balance, and the balance is never bigger than in year one. On that same loan, year one eats $2,697 of interest while the final year takes only $450, even though the payment never changes. That front-loaded math is why the first year of a bad-credit loan feels like running in place. Before you sign, check what rate your score should actually get, and learn how to negotiate a car loan rate instead of accepting the first number you are handed.
The way out is not a secret, and it is not hopeless. Interest is charged on what you borrow, so more down payment means less interest, every single time: each extra $1,000 down at 19.10% saves about $560. A shorter term starves the interest too, cutting that same loan from $8,396 over 60 months to $6,566 over 48. Stack the levers, keep the payments on time, and a year from now you can price the whole loan again with the Car Loan Total Cost Calculator at a rate your rebuilt score earns.
A second set lights the other side of the driveway. The whole car sits in the light, not just the half near the door.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Motion lights fire the second anyone steps close to the car. It is the cheapest protection you will ever buy for it, and you only buy it once.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Questions, answered
How is interest on a car loan calculated?
Each month the lender charges interest on what you still owe: your balance times the APR divided by 12. Early on, when the balance is highest, most of each payment is interest. As the balance falls, more of the same payment goes to principal. That is why interest is called front-loaded.
How much interest will I pay on a car loan with bad credit?
On a $15,000 loan at the subprime average of 19.10% (Experian Q2 2026) over 60 months, you pay $8,396 in interest on top of the $15,000 you borrowed. At the deep subprime average of 21.62%, the same loan costs $9,663 in interest. The rate band, not the car, is what makes the total climb.
Why is so much of my first payment interest?
Because interest is charged on the balance, and the balance is never bigger than it is at the start. On that same $15,000 loan at 19.10%, year one eats $2,697 of interest while the final year takes only $450, even though the payment never changes.
Does a bigger down payment really save much interest?
Yes, because interest is charged on what you borrow, and every dollar down is a dollar never charged. Each extra $1,000 down on a 60-month loan at 19.10% saves about $560 in interest, and it lowers the monthly payment by about $26 on top of that.
Is a shorter term or a lower rate better for cutting interest?
Both work, but the term is the lever fully in your hands today. That $15,000 loan at 19.10% costs $6,566 in interest over 48 months against $8,396 over 60 months, a saving of $1,830. A lower rate helps too, and after a year of on-time payments many buyers can refinance into one.
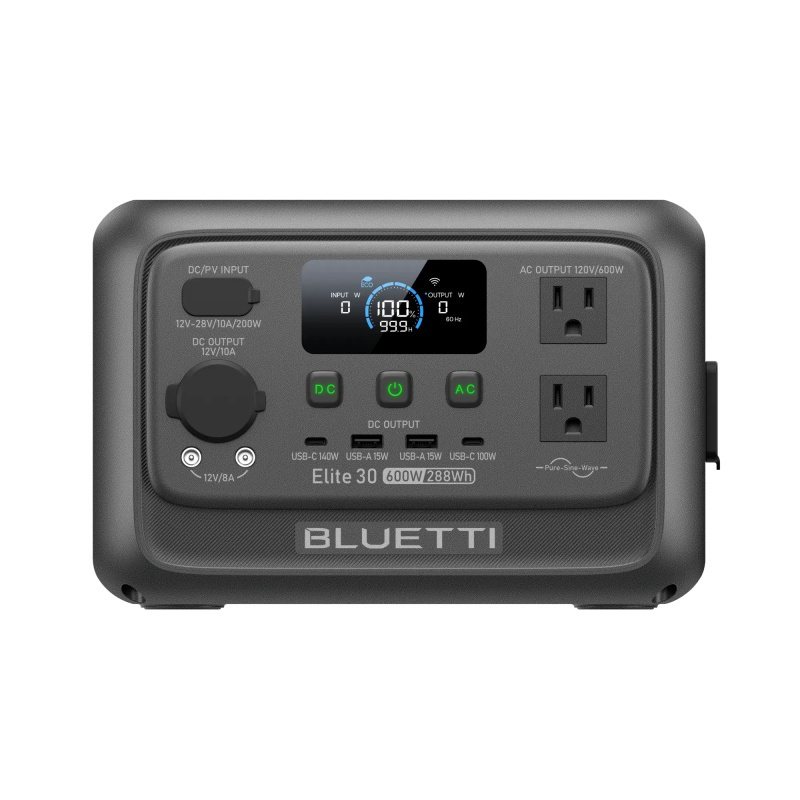
A bigger backup for longer outages: run the essentials for hours, recharge it from the sun, and never lose a fridge of food again.
$269.95 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Estimates only — not financial advice. Rates are Experian Q2 2026 averages; your actual rate depends on the lender, the car, and your full application.