Car Loan Interest Rate by Credit Score Calculator
Real average rates by score band — Experian Q2 2026 data — plus what it means for your payment.
 6X4 STORAGE SHED
6x4 Ft Brown Outdoor Storage Shed — Lockable Double Doors
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Rate data: Experian State of the Automotive Finance Market, Q2 2026. Averages — your actual rate depends on lender, vehicle, term, and down payment.
 2-PACK SOLAR LIGHTS
3-Head Solar Security Lights — 2 Pack
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 OBD2 SCANNER
V519 OBD2 Scanner — Read the Codes Before You Buy
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Your score is a price tag
Lenders don’t see a person — they see a risk number, and they price every loan off it. The numbers above are real national averages from Experian’s Q2 2026 auto finance report: a deep-subprime buyer pays around 21.6% on a used car while a super-prime buyer pays 6.3% on the same lot. On an $18,000 loan, that gap is roughly $8,000 in interest.
These are averages, not quotes — your actual rate depends on the lender, the vehicle’s age, the loan term, your down payment, and whether the dealer marks the rate up (it happens — check with our markup calculator). But knowing the average before you walk in is power: if a dealer quotes you far above your band’s average, you know something’s off.
 SOLAR POWER BANK
20,000mAh Solar Power Bank
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 TIRE INFLATOR
Portable Tire Inflator — Cordless, 150 PSI
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
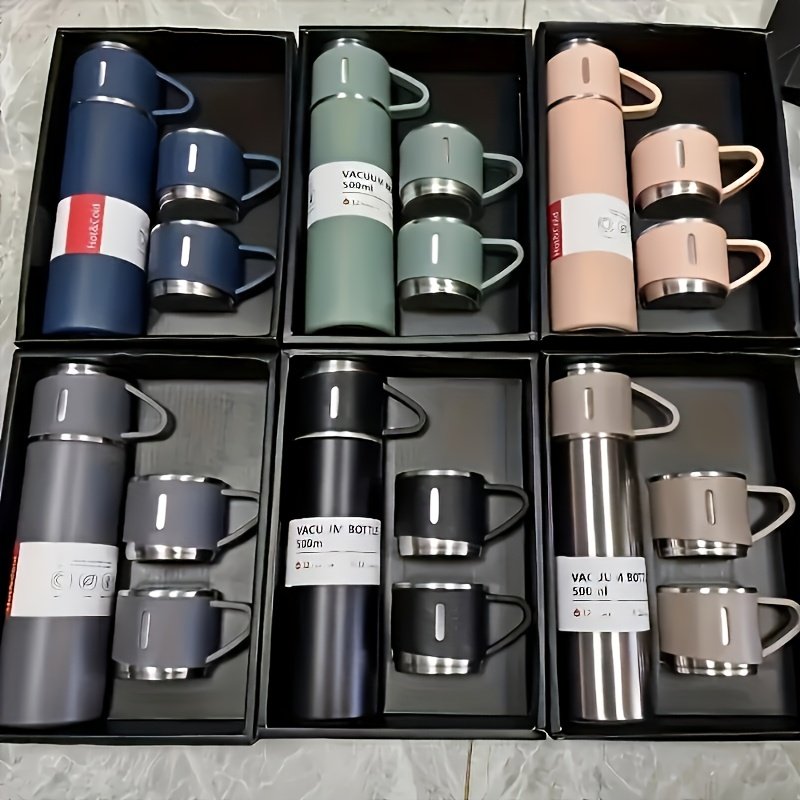 INSULATED CUP SET
Insulated Cup Set — 4 Bottles & Cups
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Questions, answered
What interest rate will I get with a 550 credit score?
Around 13.5% new / 19.1% used on average (Experian Q2 2026) — but subprime quotes range widely, so shop at least 3 lenders. Buy-here-pay-here lots often charge more than the average.
What credit score do I need for a good car loan rate?
661+ (prime) gets you under ~9% on average; the real savings kick in at 781+ (super prime), where used-car averages sit around 6.3%.
Why is my rate higher than the average for my score?
Averages hide dealer markup, loan term, vehicle age, and lender overlays. Your quote includes all of those — compare your offer against the table, not just the average.
Do auto lenders use FICO or VantageScore?
Most use FICO Auto Score — not the score you see on free apps, which is often VantageScore. Expect the lender’s number to differ slightly from yours.
Can I get a better rate after I buy?
Yes — refinance after 6–12 months of on-time payments if your score improves. Your first loan doesn’t have to be your last.
Moving your rate before you buy
You can’t fix your credit in a week, but you can often move your rate. First, pull your actual auto-enhanced score — dealers use auto-specific FICO versions that can differ from the number on your credit card app by 20 points or more, and the difference can mean a whole pricing tier. Second, pay down credit card balances below 30% of the limit if you can; utilization is the fastest-moving part of your score. Third, don’t let six dealers pull your credit — rate-shop within a 14-day window so the inquiries count as one. And fourth, bring a competing offer. A preapproval letter from a credit union, even at a high rate, is leverage. The finance office can often beat it, but only if they know it exists.
Estimates only — not financial advice. Rate averages shown, not quotes.