Down Payment Savings Calculator
Turn “someday” into a date. See exactly when your down payment will be ready.
 SOLAR POWER BANK
20,000mAh Solar Power Bank
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 2-PACK SOLAR LIGHTS
3-Head Solar Security Lights — 2 Pack
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 TIRE INFLATOR
Portable Tire Inflator — Cordless, 150 PSI
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
A date beats a dream
“I need to save for a down payment” is a wish. “I’ll have $2,500 by March 14th” is a plan — and plans get finished. Breaking a big scary number into a weekly amount makes it real: $75 a week is a skipped DoorDash order and a flipped item on Marketplace, not a second job.
Here’s the part nobody tells you: every week you save also buys you negotiating power. Walking onto a lot with cash in hand changes how dealers treat you. The down payment is the one part of a bad-credit deal you fully control — your score is history, but your savings are a choice you make this week.
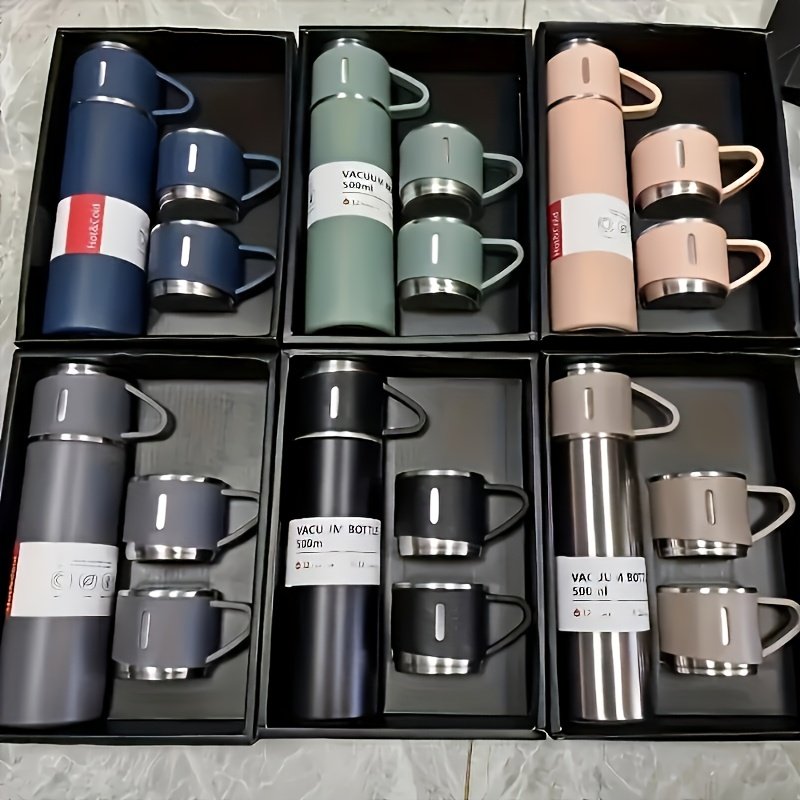 INSULATED CUP SET
Insulated Cup Set — 4 Bottles & Cups
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 6X4 STORAGE SHED
6x4 Ft Brown Outdoor Storage Shed — Lockable Double Doors
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
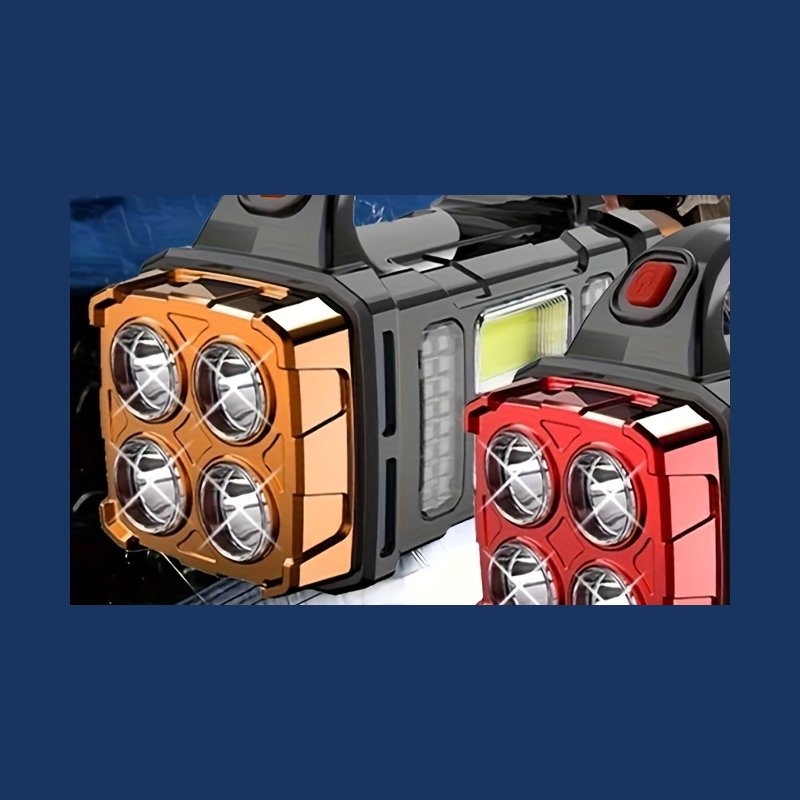 SOLAR LANTERN
Solar & USB LED Lantern — COB Work Light
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Questions, answered
How much should I save for a car down payment?
With bad credit, aim for 10–20% of the car’s price ($1,000–$2,000 on a typical $10k–$15k car). More down means better approval odds.
How fast can I save $1,500 for a down payment?
At $60/week, about 6 months. At $100/week, under 4 months. The calculator above gives you your exact date.
Should I save the down payment or pay down debt first?
If your score is under 600, the down payment usually wins — it directly unlocks approval, while small debt paydowns may not move your score fast enough.
Where should I keep my down payment savings?
A separate savings account you don’t touch. Not invested, not in cash at home — somewhere boring and safe.
What if I can’t save the full amount?
Save what you can and pair it with a cheaper car or a co-signer. An $800 down payment on an $8,000 car beats $0 on a $15,000 car.
Where the money actually comes from
Forget budgeting apps for a minute. The fastest down payments come from three places. One: sell what you’re not using. The average garage holds $500 to $1,000 in dead weight — old phones, tools, a TV, clothes with tags still on. List it this weekend; priced to move, it sells in days. Two: stack short-term gig income and quarantine it. A month of evening deliveries or weekend moving help, with every dollar going into a separate savings account you don’t touch, is $600 to $1,200 for most people. Three: pause two subscriptions and redirect the money. It’s not the $30 a month that changes things — it’s the proof to yourself that the goal is real. The people who hit their number fastest aren’t the ones who earn the most. They’re the ones who gave the money a job and a deadline, then protected that deadline like it mattered. Because it does — every month you wait is another month of bus fare, rideshares, or a dying car.
Protect the stash
One rule while you’re saving: the down payment fund is not an emergency fund, and the emergency fund is not the down payment fund. If you raid the car money every time life happens, you’ll never hit the number. Keep it in a separate account — ideally one without a debit card attached — and treat the weekly transfer like a bill. Future-you, driving your own car, will be glad past-you was stubborn about it.
Estimates only — not financial advice.