Do I Still Owe Money After My Car Is Repossessed?
They took the car — so are you done? Two numbers give you the plain answer.
 6X4 STORAGE SHED
6x4 Ft Brown Outdoor Storage Shed — Lockable Double Doors
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
There’s hope here: that leftover amount is now unsecured debt — like a credit card balance. Debts like this are commonly settled for 40–60% of what’s owed, especially once a collection agency has it. Don’t pay the first number they quote you.
 2-PACK SOLAR LIGHTS
3-Head Solar Security Lights — 2 Pack
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 OBD2 SCANNER
V519 OBD2 Scanner — Read the Codes Before You Buy
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Why you can still owe money with no car
Getting the car taken doesn’t erase the loan. The lender sells your car at an auction — and auction prices are brutal. A car that was worth $12,000 on a dealer lot might bring $6,000 at auction. Then the lender adds the cost of the tow truck, the storage lot, and the auction itself to your bill.
Whatever is left over after the sale — the amount the auction didn’t cover — is what lenders call a deficiency balance. It’s just the leftover. And yes, in most states they can bill you for it, take you to court over it, and even garnish your wages. But here’s what they won’t tell you: without the car backing it up, that debt is now unsecured — and unsecured debts get settled for far less than the asking price all the time.
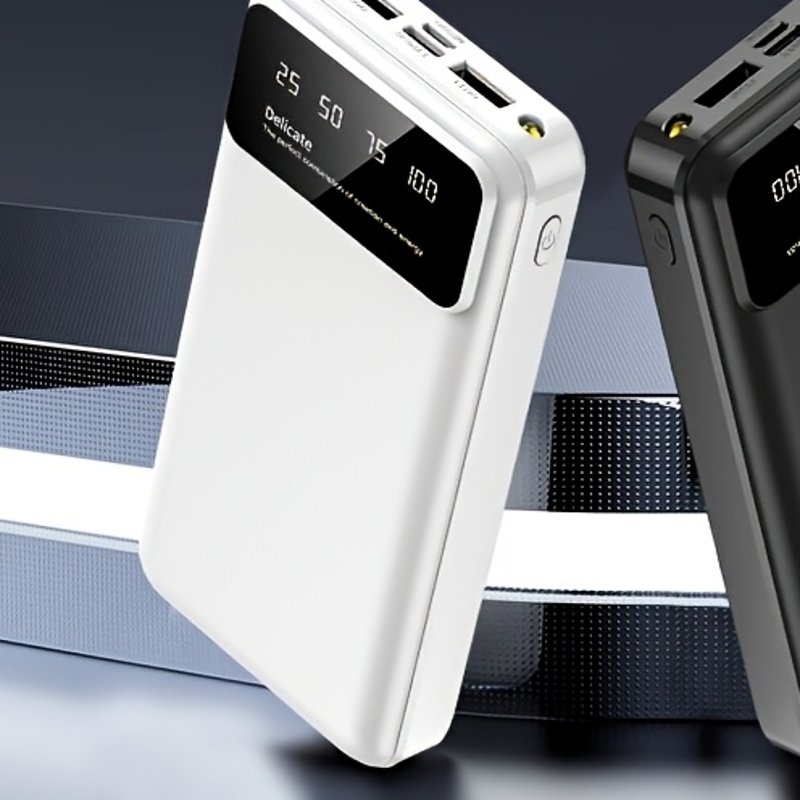 50,000MAH POWER BANK
50,000mAh Power Bank — Big Backup Battery
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 TIRE INFLATOR
Portable Tire Inflator — Cordless, 150 PSI
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
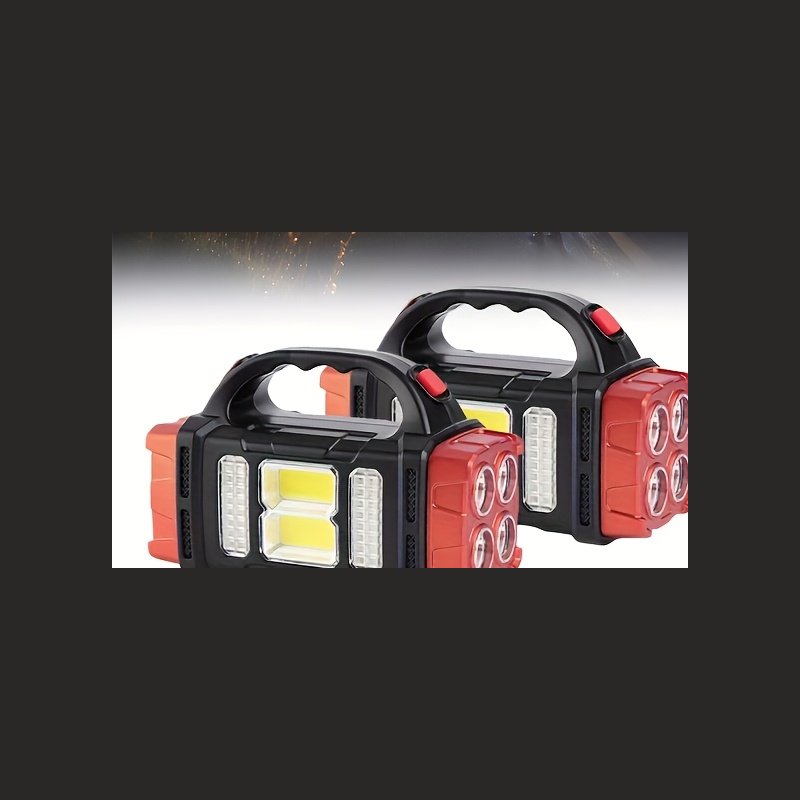 SOLAR LANTERN 2-PACK
2-Pack Solar LED Lanterns — Buy 1 Get 2
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Questions, answered
Do I still owe money after my car is repossessed?
Almost always, yes. The auction sale rarely covers the full loan — repo cars sell for 30–50% of retail — so there’s usually a leftover amount the lender can come after you for.
What happens if I don’t pay what’s left?
The lender can send it to collections, sue you, get a court judgment, and in many states garnish your wages. It also sits on your credit report. Ignoring it usually makes it worse — but you don’t have to pay the full asking price either (see below).
Can I settle or negotiate the leftover amount?
Yes — this is your best leverage. Once the car is gone, the debt is unsecured, like a credit card. Leftover balances like this are commonly settled for 40–60% of what’s owed, especially when a collection agency holds the account. Never accept the first number.
Can the lender garnish my wages for it?
In many states, yes — but only after suing you and winning a court judgment. They can’t just start taking your paycheck. State rules vary a lot, so look up yours or talk to a consumer attorney (many give free consultations).
How do I find out what my car sold for?
The lender is required to send you a written accounting — what the car sold for, every fee they added, and the leftover balance. If you never got one, demand it in writing before you pay anything. If the numbers look wrong (car sold suspiciously cheap), you can challenge them.
Estimates only — not financial advice and not legal advice.