How Much Car Can I Afford with Bad Credit? — Approval Calculator
The dealer asks, “What payment can you do?” Wrong question. Lenders run two checks on your pay and your debts before they ever talk price — this calculator runs those same two checks, with real average rates for your credit score, so you hear your number here first.
 6X4 STORAGE SHED
6x4 Ft Brown Outdoor Storage Shed — Lockable Double Doors
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 OBD2 SCANNER
V519 OBD2 Scanner — Read the Codes Before You Buy
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
 2-PACK SOLAR LIGHTS
3-Head Solar Security Lights — 2 Pack
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
The two checks every lender runs — now you can run them first
Here is the blunt truth nobody at the dealership tells you: a lender never asks, “Can this person afford this car?” They run two colder checks. The payment check asks whether the payment — with insurance counted in — fits inside 15% to 20% of your pay before taxes. The debt check asks whether everything you pay each month — rent, cards, loans, and the new car payment together — stays under roughly half your pay. If either check fails, the answer is a smaller car or a no. That is the whole game, and now you have played it before they have.
So if the number above is smaller than the car you pictured, do not read it as a verdict. Read it as a map. It tells you exactly which wall you hit — your payment window, your other debts, or your down payment — and every one of those walls has a door in it. The down payment is usually the first door: it is the one obstacle fully in your hands, and it is smaller than you think. The down payment calculator shows the tiers by score, and the obstacle guide shows how real people stack the cash.
And the car you buy at this number is not just transportation. Financed through a lender that reports your payments — ask, before you sign, whether they report to all three credit bureaus — it is also the machine that moves your score into a cheaper rate band. Six to twelve months of on-time payments, and the refinance math starts working in your favor. Start with the car you can actually carry. Let it rebuild everything else.
 SOLAR POWER BANK
20,000mAh Solar Power Bank
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Approval is only half the picture. The other half is what the payment does to your real life — rent, food, the shift you cannot miss. For that side of the question, run the How Much Car Can I Afford Calculator, which works from your take-home pay instead of the lender’s checks.
Questions, answered
How do lenders decide how much I can borrow with bad credit?
Two checks. First, the payment check: your payment plus insurance typically has to stay between 15% and 20% of your pay before taxes. Second, the total-debt check: your rent, your other monthly debts, and the new payment together typically have to stay under 45% to 50% of your pay. Whichever check gives the smaller number is the one that decides.
What interest rate will I get with bad credit?
It depends on your score band. Experian’s Q2 2026 averages for used cars: 21.62% under a 500 score, 19.10% at 501–600, 13.93% at 601–660, and 8.81% at 661 and up. Your real rate is the lender’s call — the car, your job, and your down payment all move it — but these averages are the honest starting point.
How much down payment do subprime lenders require?
Most want $1,000 or 10% of the car’s price, whichever is less — that is typical subprime lender practice, not a law. It is also why a $500 down payment opens a $5,000 car but not a $12,000 one: 10% of $5,000 is $500, and the rule takes the smaller number.
My debts are high. Can I still get approved?
Possibly — for a smaller car. If your rent and other debts already use up most of the total-debt guideline, the room left decides your price, not your paycheck alone. Paying off one small monthly debt frees up room dollar for dollar, and it is usually the fastest way to raise the car you can buy.
Is a 72-month loan a good way to afford more car?
It lowers the payment, but at bad-credit rates the interest piles up fast and you can owe more than the car is worth for years. This calculator offers 48, 60, and 72 months so you can see the trade — most of the time, a cheaper car on a shorter loan beats a nicer car stretched thin.
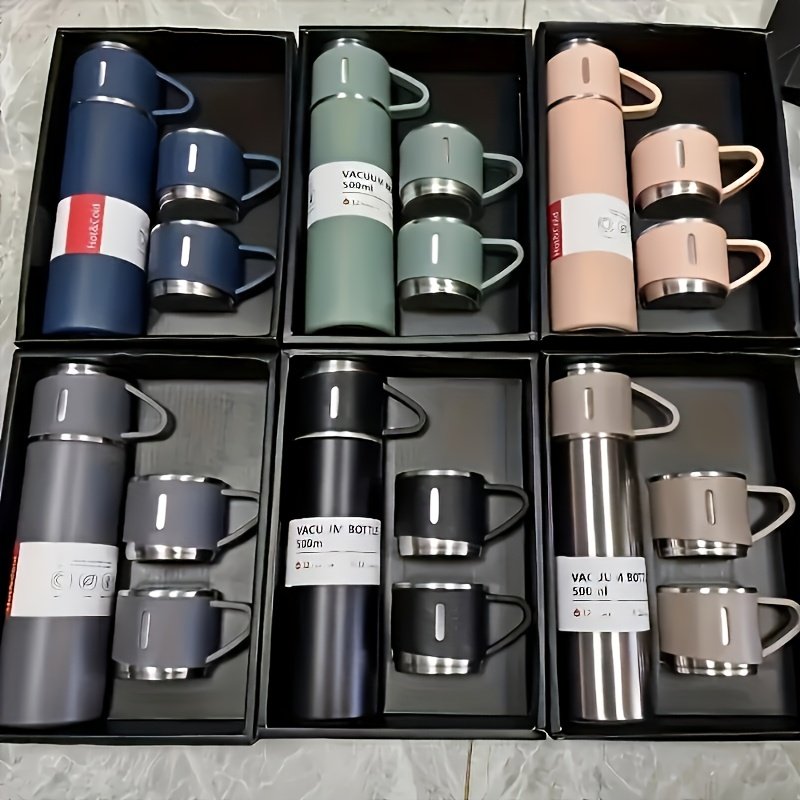 INSULATED CUP SET
Insulated Cup Set — 4 Bottles & Cups
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
The honest note: this calculator runs on averages and typical lender rules — Experian’s Q2 2026 average rates, and the payment and debt checks subprime lenders typically use. It is not a promise of approval. The lender makes the final call, and they look at the whole picture: the car, your job, your history. Use the number to walk in prepared, not surprised.
Rates: Experian, State of the Automotive Finance Market, Q2 2026 (average used-car APR by score band). Payment and debt caps and the down payment floor: typical subprime lender practice as published by CarsDirect and Auto Credit Express. The insurance figure is a rough estimate scaled to the loan size — your real quote will differ.
 TIRE INFLATOR
Portable Tire Inflator — Cordless, 150 PSI
Affiliate disclosure: we may earn a commission if you buy through these links, at no extra cost to you.
Estimates only — not financial advice.