Car Loan Refinance Calculator
You made your payments on time. Now find out what that discipline is worth: your current loan against a new one, payment and total interest side by side — including the trap most refinance offers hide.

You earned this refinance with on-time payments — protect the car that got you here with lights that watch it every night.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.

Put the monthly savings somewhere useful: end the storage-unit bill and keep your gear locked up at home instead.
$137.21 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Watch the term, not just the payment. Stretching the loan over more months can lower your monthly payment while costing you MORE total interest — you pay longer, so you pay more. If the “total interest you save” number above is negative, the refinance is a bad deal wearing a friendly payment. Compare the two total-interest lines, always.
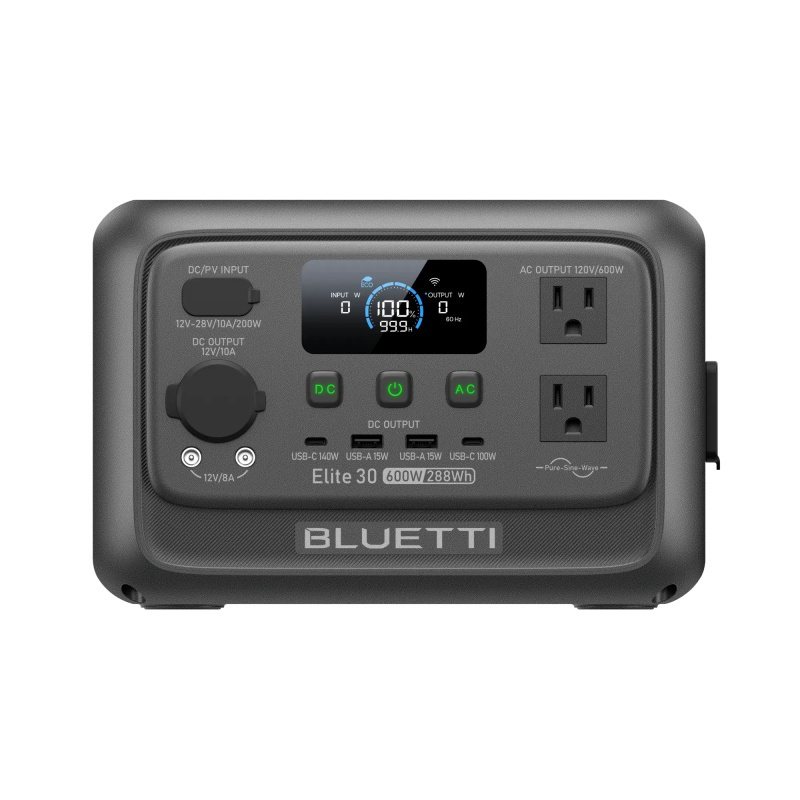
Monthly savings plus real backup power for blackouts — this keeps the lights, phone, and fridge on when the grid quits.
$269.95 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
When refinancing actually works — and when it is a trap
A refinance is simple: a new lender pays off your old loan, and you pay the new lender instead, hopefully at a lower rate. The honest doctrine is this: refinancing works best after 6–12 on-time payments. That is because on-time payments are what raise your score, and your score is what buys the cheaper rate. Refinance too early, with the same score, and you mostly get the same rate with fresh paperwork.
Look at the band presets above. Going from subprime (19.10% average used rate, Experian Q2 2026) to near prime (13.93%) is not a fantasy — it is what a year of clean payments does for a lot of buyers. On a $9,000 balance that drop can save well over a thousand dollars of interest. That is real money, earned one on-time payment at a time.
But watch the trap this calculator is built to expose: a lender can make any payment look small by stretching the term. Lower payment, more months, more total interest — the warning block above the verdict exists because that trade hides in almost every refinance offer. Compare total interest to total interest, never payment to payment. For the full walkthrough, read how to refinance a bad-credit car loan, check whether you are upside down on the loan first (owing more than the car is worth can block a refinance), and if the numbers say wait, the payoff calculator shows what extra payments do in the meantime.
A second set for the back of the house, so the car is covered from every angle, not just the street side.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
The interest you save can buy this outright — and it keeps saving you the storage fee every month after.
$137.21 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Questions, answered
When should I refinance my car loan?
For most bad-credit buyers, the sweet spot is after 6–12 on-time payments. That streak lifts your credit score, and a higher score is what unlocks a meaningfully lower rate. Refinancing before your score moves usually just restarts the clock at a similar rate.
Can refinancing hurt me if the payment goes down?
Yes — if the lower payment comes from a longer term instead of a lower rate. More months of payments can mean more total interest even at a slightly better rate. Always compare total interest, which this calculator puts side by side.
How much can I save by refinancing from 19% to 14%?
On a $9,000 balance with 48 months left, dropping from 19.10% to 13.93% cuts the payment by about $24 a month and saves roughly $1,150 in total interest — if you keep the same term. Stretch the term and some or all of that saving disappears.
Can I refinance if I owe more than my car is worth?
It is harder. Most lenders will not refinance a loan that is far upside down, because the car is their collateral. Paying the balance down first — or waiting until payments and the car's value meet — is usually the path. Check with our upside-down calculator.
Does refinancing my car loan hurt my credit?
Expect a small, temporary dip from the credit inquiry and the new account. It typically recovers within a few months of on-time payments, and the lower rate saves real money in the meantime.
The refinance lowered your payment; these lower your risk. Motion lights on the car, every night, for $22.26 once.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Estimates only — not financial advice. Rates are Experian Q2 2026 averages; your actual rate depends on the lender, the car, and your full application.