When Can I Refinance My Car Loan With Bad Credit?
Quick answer: You can usually refinance a car loan with bad credit after 6 to 12 months of on-time payments, as long as your score has improved and you don't owe more than the car is worth. Your first loan doesn't have to be your last — refinancing is how you escape a 20% rate you only accepted because you had no choice.

Recommended · Temu
V519 OBD2 Scanner — Check Engine Code Reader
Before you sign for that used car, plug this in under the dash and read the codes yourself. It shows check-engine codes and live data — the stuff a seller hopes you never check. 4.6 stars, 28K+ sold on Temu.
$17.01 on Temu
See the scanner on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The Loan You Signed Wasn't the Loan You Deserve
Let's be honest about how you got here. Your credit was wrecked, you needed a car, and somebody said yes at 19% interest on a car that was already worth less than the loan. You signed because you had to. Nobody in that room was doing you a favor.
But here's the thing nobody told you that day: that loan was temporary. It was a bridge, not a life sentence. Every on-time payment you've made since is a brick in a new road — and refinancing is the exit ramp off the rate that's been eating you alive.
When You're Actually Ready
There's no magic date, but there's a pattern that works. Most people can refinance somewhere between 6 and 12 months after the original loan, if three things are true:
Your score went up. It doesn't have to be great. Going from 520 to 580 changes the conversation. Going from 580 to 620 changes it a lot more. Even 40 or 50 points of improvement, all from on-time car payments, tells a new lender a different story about you than the old lender heard.
You don't owe more than the car is worth. This is the one that kills most refinance attempts. If you put little down and the car depreciated fast, you might owe $14,000 on a car worth $10,000. Lenders won't refinance that — they won't lend more than the collateral is worth. If you're close, sometimes bringing a few hundred dollars to the table closes the gap.
You have steady income you can prove. Pay stubs, bank deposits, tax returns. Same paperwork as last time, but now you're walking in as someone with a track record instead of a prayer.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Who Actually Refinances Bad Credit
Not every lender does. Your big banks mostly won't touch subprime refinances. But these will:
Credit unions are the best-kept secret in this whole game. They look at you like a person, not a number. Many credit unions refinance members with scores in the mid-500s and up. If you're not in one, joining is usually free or close to it.
Online refinance lenders exist specifically for this. They compete for your business, which means better rates than walking into the same bank that already has you at 19%.
The lender you already have — sometimes. It sounds backwards, but calling your current lender and asking about a rate reduction costs nothing. They'd rather keep you at 12% than lose you to someone else at 11%. The worst they say is no.
What Refinancing Actually Saves You
Let me put real numbers on this, because hope needs math to be useful.
Say you owe $12,000 at 19% with 48 months left. Your payment is roughly $360 a month. Refinance that same $12,000 at 11% and the payment drops to about $310 — and you pay thousands less in interest over the life of the loan. That's $50 a month back in your pocket and real money saved overall.
That's not a fantasy. That's what 8 points of interest does on a car loan.
Recommended · Temu
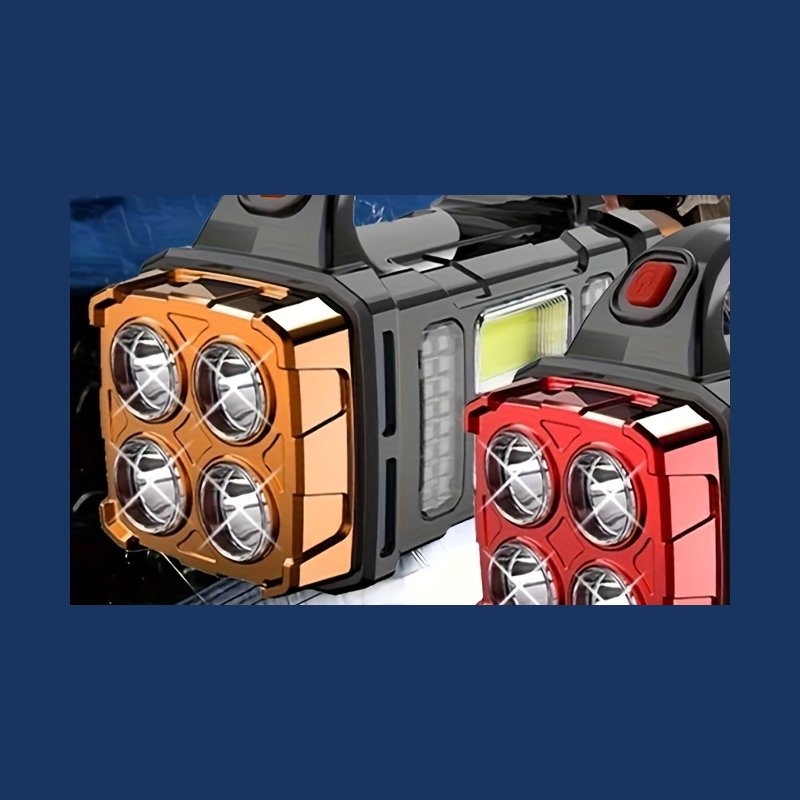
Solar & USB LED Lantern — COB Work Light
When the power goes out, this is your light. It charges from the sun or any USB port — no candles, no wiring, nothing to install. 4.7 stars, 100K+ sold.
$4.94 on Temu
See the lantern on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The Traps to Dodge
Don't extend the term to get the payment down. A lender offers you 72 months at a lower payment and it feels like relief. But you're paying interest for two extra years on a car that keeps losing value. If you refinance, keep the term the same or shorter.
Don't roll in extra debt. Some lenders will let you roll credit card balances or fees into the refinance. Now your car secures someone else's debt. Say no.
Watch the fees. Application fees, title transfer fees, prepayment penalties on your OLD loan. Add them up before you sign. A refinance that costs $800 in fees to save $900 in interest isn't worth the paperwork.
Your Move
Pull your credit score today — free, no harm, takes two minutes. Then call your current lender and one credit union and ask two questions: "What's my current rate?" and "What would you offer me to refinance?" That one afternoon of phone calls is the difference between paying 19% for four more years and paying 11%.
The first loan got you the car. The refinance gets you your money back.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Stuck in a high-APR loan? This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) protects the car you're refinancing — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
21V Cordless Drill Kit — Full Tool Set in a Case
Every repair you do yourself is a payment you don't finance. This 21V drill kit comes with the bits and hand tools to start — brakes, batteries, and the small stuff. 4.7 stars, 49K+ sold.
$12.69 on Temu
See the drill kit on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
How long do I have to wait to refinance a car loan with bad credit?
There's no legal waiting period. Most lenders want to see 6 to 12 months of on-time payments on the current loan before they'll refinance you, because that payment history is the proof your credit is actually improving.
What credit score do I need to refinance a car?
It depends on the lender, but many credit unions and online lenders refinance borrowers in the mid-500s and up. The higher your score, the better the rate — even moving from 550 to 600 can shave meaningful points off your interest rate.
Does refinancing a car loan hurt your credit?
The application causes a small, temporary dip from the hard inquiry — usually a few points for a few months. But the long-term effect is positive: a lower rate makes payments easier to keep current, and on-time payments are what build your score.
Can I refinance if I still owe more than my car is worth?
Usually not through a standard refinance — lenders won't lend more than the car's value. Your options are to pay down the difference, bring cash to closing, or wait until depreciation and your payments bring the balance in line with the car's worth.