Car Loan Payoff Calculator
At bad-credit rates, interest eats your payment alive. This shows exactly what one extra payment a month does: how much sooner you are done, and how much interest you keep in your own pocket.

Money saved on interest deserves a job: this shed ends the monthly storage-unit bill so the savings keep stacking.
$137.21 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.

While you pay the car off, keep it protected where it parks — motion lights that cost less than one month of interest at subprime rates.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
A second set watches the other side of the driveway, because a paid-off car you own free and clear is worth guarding.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Why extra payments hit so hard at bad-credit rates
Here is how a car loan really works: every month, the lender first takes interest out of your payment, and only what is left touches your balance. At 19% or 21%, that interest bite is huge — early on, half your payment or more can vanish into interest before your balance moves a dollar. That is why the loan feels stuck. It is not you. It is the math.
An extra payment skips the line. Money you send on top of your regular payment goes straight at the balance (tell your lender to apply it to principal — say those words). A smaller balance means less interest next month, which means more of every regular payment hits the balance, which means the whole loan starts sliding downhill faster and faster. The calculator above runs that month-by-month math honestly, so the interest-saved number is real, not a sales pitch.
One caution, in plain words: keep a small emergency cushion first. A paid-down loan does not help if a flat tire puts you back on a credit card at 29%. Build a starter buffer, then attack the loan. And when the balance gets low enough and your score has climbed from those on-time payments, check whether a refinance beats paying it off — and see how the payoff path compares with refinancing a bad-credit loan in full. Either way, the direction is the same: less interest, sooner free. For the bigger picture on escaping the down-payment trap next time, read the down payment obstacle.
Store your own tools and do the small jobs yourself — every shop bill you skip is another extra payment on the loan.
$137.21 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
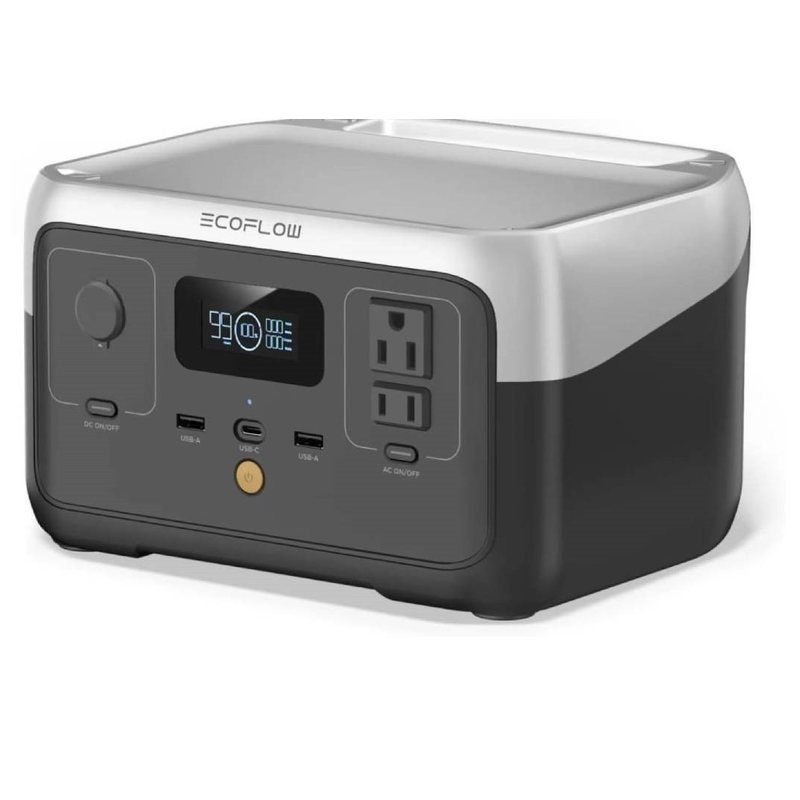
One dead battery or blackout can wreck a tight payoff budget. This is the backup that keeps a bad day cheap.
$186.29 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Questions, answered
How much interest can I save by paying extra on my car loan?
It depends on your rate and balance, and at bad-credit rates the savings are big. On a $9,000 balance at 19.10% with a $280 payment, adding $50 a month saves hundreds of dollars in interest and pays the loan off months sooner. Run your own numbers above for the exact figure.
Should I tell my lender how to apply my extra payment?
Yes — tell them: apply it to principal. If you do not, some lenders apply extra money to next month's payment instead, which does not shrink your balance or your interest. Check your next statement to confirm it landed on the principal.
Is it better to pay off my car loan early or refinance it?
If your score has improved after 6–12 on-time payments, a refinance to a lower rate can save more than extra payments alone. If your score has not moved yet, extra principal payments are the stronger play. Many people do both: pay extra now, refinance when the score climbs.
Does paying off a car loan early hurt my credit?
Closing the loan can cause a small, temporary dip because one account closes — but the record of on-time payments stays and helps you. The interest you save is real money; a few points for a few months is almost always the right trade.
What if I can only add a little extra each month?
Add it anyway. At subprime rates, even $25 a month cuts months off the loan because every dollar of principal you remove stops generating interest immediately. Small and steady beats big and someday.
The cheapest protection your car will ever get: bright motion light the second anyone gets close, all night, every night.
$22.26 on Temu
See it on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked November 2026; Temu prices change often.
Estimates only — not financial advice. Rates are Experian Q2 2026 averages; your actual rate depends on the lender, the car, and your full application.