Buying a Car in Austin After a Repo
Quick answer: Yes, you can buy a car in Austin after a repo, and there is no legal waiting period — you can apply the day after. In practice, lenders want to see steady income, some time of on-time payments on your other bills, and a real down payment — 10% to 20% is the working range. The fastest Austin path is a subprime lender or a buy here pay here lot that reports your payments, like Texas Auto Center on I-35 South, which states it reports monthly to the major bureaus. Also settle one thing first: whether you still owe a deficiency balance on the old car.

Recommended · Temu
21V Cordless Drill Kit — Full Tool Set in a Case
Every repair you do yourself is a payment you don't finance. This 21V drill kit comes with the bits and hand tools to start — brakes, batteries, and the small stuff. 4.7 stars, 49K+ sold.
$12.69 on Temu
See the drill kit on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The car is gone. That already happened, and no amount of re-reading the tow notice changes it.
Here is what nobody tells you straight: a repossession is not a life sentence on buying another car. There is no law — not in Texas, not anywhere in the United States — that makes you wait a single day before financing again. The seven-year mark people quote is how long a repo can sit on your credit report. It is not a waiting period. People in Austin finance cars months after a repo, sometimes sooner, because in this city the car is the job.
What a repo actually changes is the price of the next loan and what you have to bring to the table. That part is real, and this page will not sugarcoat it. But it is a money problem, not a permission problem — and money problems have paths.
Do you have to wait a set time after a repo to buy again?
No. This is the biggest myth in this whole subject, so let's kill it plainly.
There is no legal waiting period. No Texas statute and no federal law bars you from taking a new auto loan after a repossession. A lender can say no — lenders can say no for almost any credit reason — but that is a business decision, not a law, and a different lender can say yes the same week.
The seven years is a reporting clock, not a ban. Under the federal Fair Credit Reporting Act, a repossession can stay on your credit report for up to seven years, counted from the date you first fell behind on that loan — not from the day the car was taken. It hurts most early and fades as it ages and as newer, better history stacks on top of it. You do not wait it out. You out-build it.
Practical timing is about proof, not permission. Lenders get comfortable when whatever caused the default has steadied: steady income for several months, rent and utilities current, no new missed payments since. If the repo was last week and nothing has changed, approvals are scarce and expensive. With six months of stability behind you, subprime lenders in Austin will talk — and buy here pay here lots, which lend on income and down payment, will often talk sooner.
Do you still owe money on the car that was taken?
Maybe — and you need to know, because this number follows you.
After a repossession, the lender sells the car, usually at auction, for whatever it brings. That sale price is subtracted from what you owed, plus repo and sale costs. If the car sold for less than the balance — common, because auction prices run low — the leftover is called a deficiency balance, and in Texas the lender can come after you for it.
The Texas basics:
- The lender generally has four years to sue. Texas Civil Practice and Remedies Code §16.004 sets a four-year statute of limitations on debt actions. A collector calling about a very old deficiency is not the same as a court judgment — if you get sued, do not ignore the papers, and get advice on your specific case.
- An unpaid deficiency does not legally block a new loan. It shows on your credit picture, and some lenders will ask about it. Some buyers settle it for less; some pay it down while financing the next car. Do not pretend it does not exist and let it surprise you mid-application.
We break the whole subject down in deficiency balances after a repo — read it before you talk to any lender, so you know your number before they tell you theirs.
Recommended · Temu
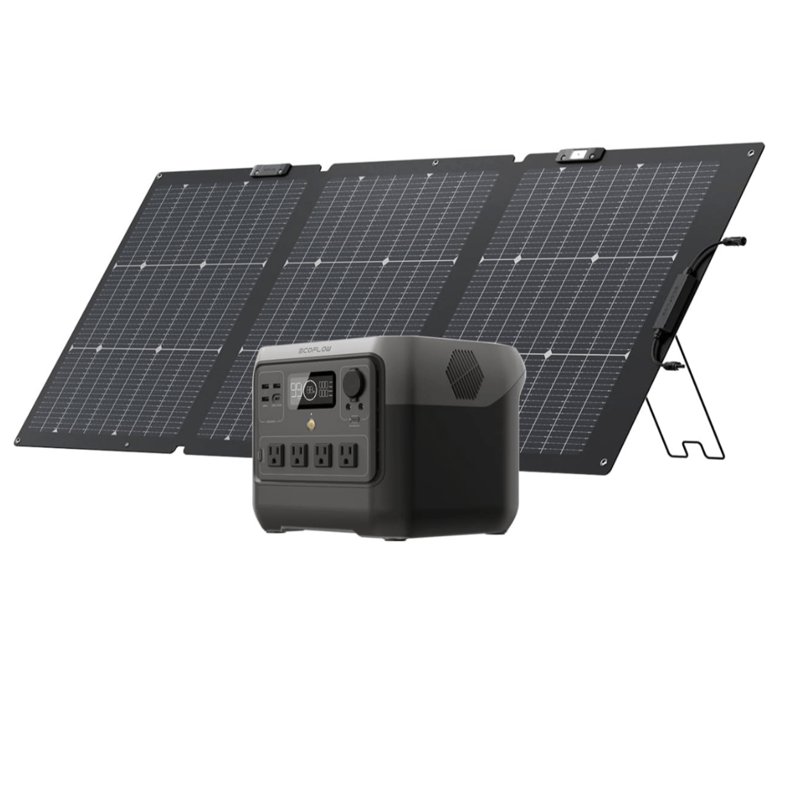
EcoFlow RIVER 2 Pro 700 Portable Power Station (716Wh LiFePO4, 800W AC)
The bigger backup: 716Wh and 800W of AC — enough for a fridge, a TV, or a work laptop through a long outage. Recharges in about 70 minutes. Silent, no fumes, safe indoors.
$327.16 on Temu
See the EcoFlow Pro on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
How do Austin lenders look at you after a repo?
The down payment is your apology and your leverage. This is the central obstacle for every bad-credit buyer, and after a repo it matters double. Most subprime lenders want 10% down or $1,000, whichever is more; after a recent repo, putting down closer to 20% moves you from "maybe" to "yes." Every extra $500 also shrinks the payment — the best protection against ever doing this again. If you are short, how much down payment you actually need will help you set a target.
Expect the rate to be steep at first. Experian's Q2 2026 averages put used-car loans at 19.10% for subprime scores (501–600) and 21.62% for deep subprime (300–500), and a recent repo usually prices you at or beyond the hard end of that range. That is the cost of re-entry. The strategy is not to love that loan — it is to survive it cleanly for a year or two, then refinance from a stronger position.
What is the smartest path back in Austin?
Step 2: Stabilize before you apply, if you can. Even two or three months of steady income and on-time payments makes a visible difference. If you need the car now to keep the job, skip to step 3 — just know the price will be higher.
Step 3: Choose a lender whose payments rebuild you. Our broader guide to getting a car loan after a repossession covers the lender types in depth. In Austin, you have two lanes:
- Subprime lenders working through dealers on the I-35 corridor, plus online preapprovals. They report to the bureaus as a matter of course, and a written preapproval gives you a ceiling and a rate to beat.
- A buy here pay here lot that reports. Reporting is voluntary at BHPH lots, and the CFPB warns many report only late payments — the worst of both worlds. The standard to demand: Texas Auto Center, 6809 I-35 South, whose own site says it reports monthly payments to the major credit bureaus, with down payments typically 10% to 20%. Whichever lot you use, get the reporting promise in writing.
Step 4: Buy below your approval, not at it. Choose the cheapest reliable car that does the job. Get a mechanic's inspection before you sign — Texas ended the annual safety inspection on January 1, 2025, so nobody checks the car for you — and prove it passes the emissions test Travis and Williamson counties still require for gasoline cars 2 to 24 years old (maximum station charge $11.50), because a car that cannot pass cannot be registered to you.
Step 5: Protect the second chance like it is the last one. In Texas, a lender can repossess without a court order and without warning once you are in default — the only hard limit is no "breach of the peace" (Texas Business & Commerce Code §9.609). A second repo is far harder to finance past than a first. Set the payment against your worst month, keep a small repair reserve, and let 12-plus months of reported on-time payments do their work. The path is not fast or cheap, but it is real — and it starts whenever you are ready, not seven years from now.
Recommended · Temu
Solar & USB LED Lantern — COB Work Light
When the power goes out, this is your light. It charges from the sun or any USB port — no candles, no wiring, nothing to install. 4.7 stars, 100K+ sold.
$4.94 on Temu
See the lantern on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
The repo took the car, not the driveway. This 2-pack of solar security lights (3000LM, motion sensor) keeps it lit and watched overnight — no wiring, no electrician, no monthly cost.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
1080P Video Doorbell Camera — Wireless, No Drilling
Your car sleeps in the apartment lot. This camera sticks on with no drilling, runs on a battery, and shows your front door — and who is near your car — right on your phone. 4.7 stars, 250K+ sold.
$9.98 on Temu
See the doorbell on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
How soon after a repo can I finance another car in Austin?
Legally, immediately — there is no Texas or federal waiting period. Practically, approval gets easier and cheaper with a few months of steady income and on-time payments behind you, plus a solid down payment. Buy here pay here lots that lend on income will often talk the soonest.
Does the repo have to fall off my credit report before I can buy?
No. A repo can remain on your report for up to seven years from the date you first fell behind on that loan, and lenders can see it the whole time. Many buyers finance again while it is still showing — the repo affects your rate and required down payment, not your legal ability to buy.
I still owe a deficiency balance. Can I finance another car?
Usually, yes. An unpaid deficiency does not legally bar a new loan, though some lenders will ask about it. Know the amount before you apply, and consider settling or paying it down as part of your rebuild — in Texas, a lender generally has four years to sue over the debt.
Will a buy here pay here loan actually rebuild my credit after a repo?
Only if the lot reports your on-time payments to the credit bureaus. Reporting is voluntary, and many BHPH dealers report only late payments. Ask before you sign and get a reporting commitment in writing — a loan that does not report on-time payments costs you money and rebuilds nothing.
<!-- sources: Sibling draft austin-bad-credit-loans.md (verified in that file) — Texas Auto Center, 6809 I-35 South: BHPH, reports monthly payments to major credit bureaus, down payments typically 10-20%; Texas Business & Commerce Code §9.609 — self-help repossession after default without court order or advance warning, no breach of the peace; Texas DPS HB 3297 — safety inspection ended Jan 1, 2025, emissions testing remains in Travis and Williamson for gasoline vehicles 2-24 years old, maximum station charge $11.50. Fair Credit Reporting Act, 15 USC 1681c — adverse information including repossession reportable for up to seven years, measured from the date of first delinquency (corroborated in search results citing the statute, 2026-11-06). No-waiting-period claim — corroborated by multiple post-repo lending sources in search results 2026-11-06 ("No law prevents you from buying a car after a repossession"; "no federally mandated waiting period"); framed as absence of a legal bar, with lender discretion stated. Texas deficiency balance — Texas Business & Commerce Code Art. 9 framework: lender must give notice before disposition (§9.614) and sell in a commercially reasonable manner; borrower liable for deficiency after sale proceeds are applied; Texas Civil Practice and Remedies Code §16.004 — four-year statute of limitations on debt suits (corroborated by Texas auto-deficiency law references in search results 2026-11-06). CFPB AskCFPB on buy here pay here — dealers often report only negative information; reporting of on-time payments should be confirmed in writing. Experian Q2 2026 average used APRs per SPEC (verified 2026-10-05): subprime 501-600 = 19.10%, deep subprime 300-500 = 21.62%; subprime down-payment norm 10% or $1,000, whichever is more, per SPEC. CUT: specific credit-score drop figures after a repo (100-150 points, seen in secondary sources) — varies too widely by file to state as a fact. CUT: Flash Flood Alley angle for this page — assignment allowed it only if natural; it did not fit the after-repo argument, so it was left out. CUT: any claim that a voluntary surrender is treated more leniently by Texas lenders — not verified; omitted. -->