Should You Finance or Lease a Supercar?
Quick answer: Financing means you own the car and build equity — but the monthly payment is brutal. Leasing a supercar means lower payments because you only pay for the part of the car you use, plus a big balloon payment at the end. With bad credit, financing is hard and leasing is harder — exotic lessors want strong credit, usually 720 or better.
Recommended · Temu
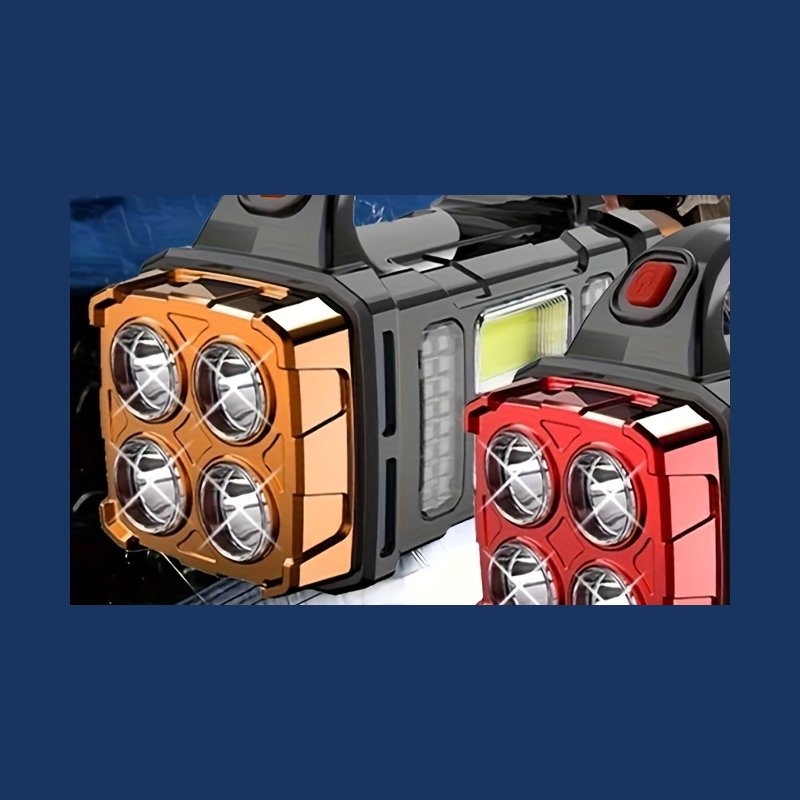
Solar & USB LED Lantern — COB Work Light
When the power goes out, this is your light. It charges from the sun or any USB port — no candles, no wiring, nothing to install. 4.7 stars, 100K+ sold.
$4.94 on Temu
See the lantern on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Here's the truth nobody tells you about supercars: the sticker price is just the cover charge. A $260,000 Lamborghini Urus financed the normal way — 20% down, 6% APR, 72 months — runs you about $3,500 a month. Miss a payment on that and the repo man drives off in something worth more than most houses.
That's why the lease question matters. On a normal car, leasing is the "cheap monthly payment" trick. On a supercar, it's a whole different animal — and for a bad-credit buyer, it's an animal that mostly doesn't want you.
How exotic leasing actually works
Forget everything you know about leasing a Honda. Exotic leasing runs through specialty companies — the big names are Putnam Leasing (30+ years in the game, finances cars from $35,000 to $1,000,000) and Premier Financial Services (their "Simple Lease" is famous in the exotic world).
Most exotic leases are open-end leases. Here's what that means in plain English: you and the leasing company agree upfront on what the car will be worth when the lease ends (the residual value). Your monthly payments only cover the difference between the purchase price and that residual — the part of the car you're "using up."
At the end, you have options: pay the residual and own it, roll it into a new lease, sell the car and pocket any difference if it's worth more than the residual, or trade it in. There's typically no mileage cap like a normal lease — because the residual was agreed upfront, the miles are your problem and your opportunity.
When leasing wins
Leasing wins on monthly cash flow, period. On that $1.5 million classic car example, a 48-month open-end lease with a 65% residual lands around $20,000 a month — versus a traditional loan that would be far higher. You're paying for the slice, not the whole pie.
There's also a tax angle: on a purchase, you pay sales tax on the whole car upfront (tens of thousands on a $400,000 car). On a lease, tax is baked into the monthly payments — you only pay tax on the part you use. If you swap cars every couple of years, that adds up.
And here's a quirk worth knowing: Putnam's leases generally don't show up on your credit report unless you fall behind. For buyers who don't want their credit lines touched, that matters.

Recommended · Temu
20,000mAh Solar Power Bank — Charges in the Sun
Your phone is your job — the lender's call, the gig app, the map. This 20,000mAh bank tops up from the sun and keeps your phone alive all shift. 4.7 stars.
$4.98 on Temu
See the power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
When financing wins
Financing wins if you actually want to OWN the thing. Every lease payment is money you'll never see again unless the car appreciates past the residual. With financing, every payment builds equity — slowly, painfully, but it's yours.
Financing also has no end-of-term surprises. On an open-end lease, if the car's market value drops below the agreed residual, YOU make up the shortfall. The lease gives you flexibility; it doesn't give you protection from a bad market.
The bad-credit reality check
Here's where I have to be straight with you: exotic leasing is harder to get than exotic financing, not easier.
Leasing companies check your credit hard. The word from actual exotic owners is you need to be above 720 to get the good deals at places like Putnam — and Woodside Credit (the big exotic lender) wants the same for their best rates. Leasing generally demands stronger credit than financing across the board, because the lessor is taking residual-value risk on top of your payment risk.
With a 500 or 600 score? An exotic lease is essentially off the table. An exotic loan is barely on it — and only with a massive down payment, usually 20% minimum, sometimes 40-50%.
So the real answer for a bad-credit buyer isn't "lease vs. finance." It's "neither yet." The path is: fix the credit, stack the down payment, then choose. A 580 score today can be a 700 score in 12 to 18 months of clean payments — and that's the difference between begging for approval and choosing your terms.
Recommended · Temu
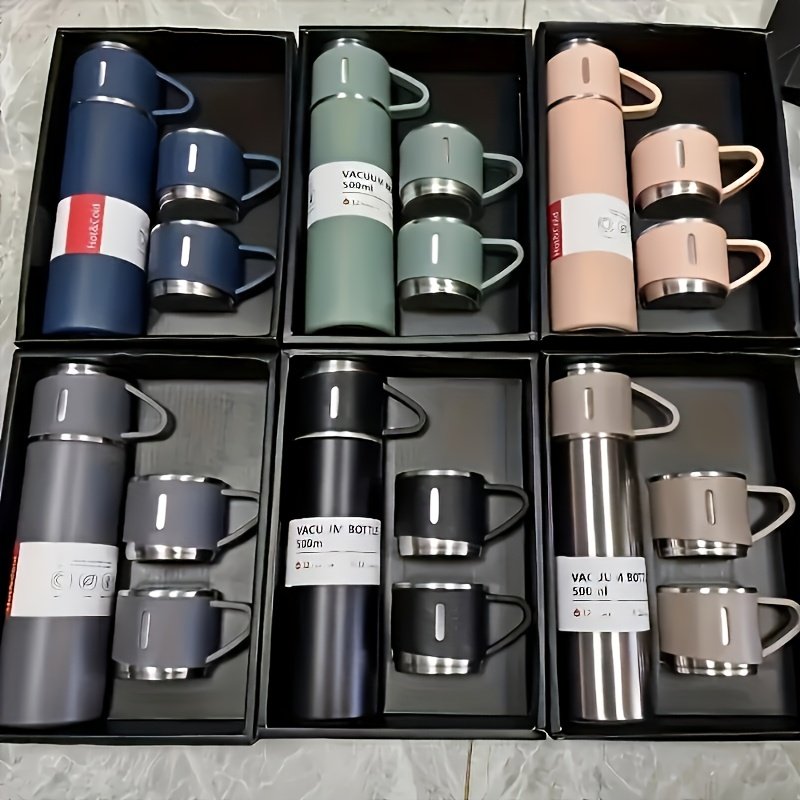
Insulated Cup Set — 4 Bottles & Cups, Gift Boxed
Coffee stays hot through a whole shift, and the set pays for itself in a week of skipped coffee runs. Four insulated bottles and cups, boxed up nice. 4.5 stars, 89K+ sold.
$5.18 on Temu
See the cup set on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The bottom line
If your credit is strong and you like swapping cars every few years, exotic leasing is genuinely smart — lower payments, tax advantages, flexibility. If you want to own the car and keep it, finance it. If your credit is bad, neither door is open yet — but the down payment you're saving and the score you're building are the keys to both.
Whether it's a Lamborghini or a Honda, the math starts in the same place: what you put down and what your credit says about you. Get those two right and the supercar conversation gets a lot more fun.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Lease or buy the dream? Either way, protect it. Solar security lights (3000LM, motion sensor) for under $20 — no wiring, no electrician.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
1080P Video Doorbell Camera — Wireless, No Drilling
Your car sleeps in the apartment lot. This camera sticks on with no drilling, runs on a battery, and shows your front door — and who is near your car — right on your phone. 4.7 stars, 250K+ sold.
$9.98 on Temu
See the doorbell on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
What credit score do you need to lease a supercar?
Exotic lessors like Putnam typically want 720 or better for their best deals. Leasing generally requires stronger credit than financing — it's not the easier path for bad-credit buyers.
Is leasing a supercar cheaper than financing?
Monthly, yes — you only pay for the depreciation slice, not the whole car. In total cost, not necessarily — and on an open-end lease you owe the difference if the car's value drops below the agreed residual.
What happens at the end of an exotic car lease?
You have four typical options: pay the residual and own it, roll the residual into a new lease, sell the car and keep any amount above the residual, or trade it in and apply the difference to your next lease.
Can you lease a supercar with bad credit?
Realistically, no. Exotic leasing companies check credit strictly and want prime scores. With bad credit, focus on rebuilding your score and saving a large down payment first — that unlocks both leasing and financing later.