Low Down Payment Cars in Indianapolis: What $500 Actually Gets You (2026)
Quick answer: In Indianapolis, the advertised floor at buy here pay here lots is around $800 down — that is Advance Auto Sales' own advertising on Pendleton Pike and East Washington Street, plus tax on top. $500 alone usually is not enough cash to drive off, but $500 saved is most of the fight, because your down payment matters more than your credit score at these lots.

Recommended · Temu
1080P Video Doorbell Camera — Wireless, No Drilling
Your car sleeps in the apartment lot. This camera sticks on with no drilling, runs on a battery, and shows your front door — and who is near your car — right on your phone. 4.7 stars, 250K+ sold.
$9.98 on Temu
See the doorbell on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
Let me tell you what $500 actually is in this game: it is proof. Proof to the dealer that you can put money together, and proof to yourself that you can carry a payment — because if you can save $50 a week for ten weeks, you have basically been making a car payment already, just to your own sock drawer.
Here is the honesty part. Do not walk onto Pendleton Pike expecting a $500-down miracle. Indianapolis lots advertise deposits starting around $800, and $800 down is not $800 to drive off — tax and fees ride on top. Walk in with your eyes open and your total number known, and the down payment stops being a trap and starts being a tool.
The Down Payment Is the Whole Game
Nobody told you this, so I will: your credit score is not what is keeping you out of a car in Indianapolis. It is the cash you hand over at the lot.
An in-house dealer protects himself with your down payment. It is the money that stands between him and a total loss if you walk away in month two. That is why Advance Auto Sales leads its advertising with the deposit number — as low as $800 plus tax, at its lots on Pendleton Pike, East Washington Street, and Madison Avenue — and why Johnny's Auto Motor on Pendleton Pike ran a special starting at $1,900 down. Same corridor, two very different doors. The advertised number tells you which buyers the lot is built for.
The realistic Indianapolis range is $500 to $1,500 for most bad-credit buyers, with the true in-house floor sitting near that advertised $800. A few hundred more changes which cars you can pick from.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What $500 Actually Gets You
Straight talk: $500 by itself probably does not drive a car off a Pendleton Pike lot in 2026. Here is what it does get you.
It gets you most of the way to the advertised floor — $300 more and you are at Advance's advertised deposit. It gets you taken seriously, because a buyer with cash in hand is a different buyer than a buyer with a story. And combined with a tax refund, it closes the deal.
Once you are in, the car itself is an older, higher-mileage get-to-work car — the kind of car that gets a warehouse worker from the east side to a shift by the airport, which is exactly the job a car does in this spread-out city. $1,500 down gets you a better pick of the lot and a lower biweekly payment. Every extra hundred down is a hundred you are not financing at a rate that can run up to Indiana's 25%-a-year ceiling — so it saves you twice.
Down Payment Is Not Drive-Off Money
This is the part that burns first-time buyers, so read it twice.
The advertised deposit is not the total cash to leave with the car. On top of it: sales tax — Advance says it right in the ad, "$800 down plus tax" — plus title and registration fees and whatever the contract lists. Ask every lot the only question that matters: "What is my total cash out the door today?"
And here is the Indianapolis-specific warning: Indiana gives you no legal grace period if you fall behind. This state has no right-to-cure law — the lot does not have to warn you before a repossession. So a down payment plan that leaves you with zero dollars in reserve is a plan to lose the car. Keep a cushion. A slightly cheaper car plus $300 still in the bank beats a nicer car and an empty account, every time, in a no-cure state.
Recommended · Temu
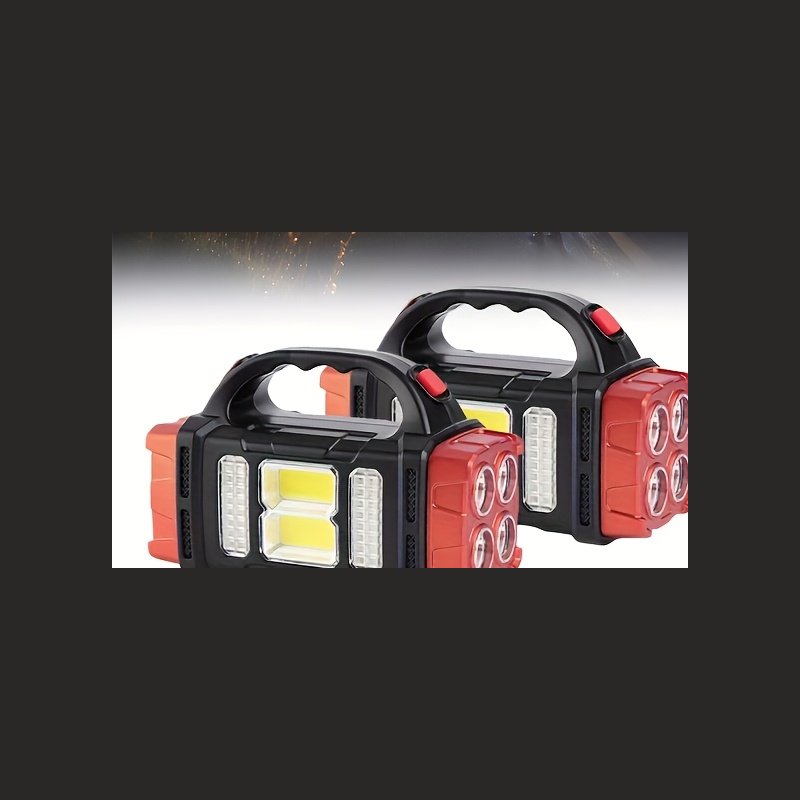
2-Pack Solar LED Lanterns — Buy 1 Get 2
Two solar lanterns for under nine bucks — one for the house, one for the car. They charge in the sun and light up a room when the grid goes down. 4.7 stars, 38K+ sold.
$8.61 on Temu
See the lantern 2-pack on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
How to Raise It Fast
Save $50 a week for 10 weeks. That is $500. Sixteen weeks is $800 — the advertised floor. Boring, and it works.
Sell what you are not using. Phones, tools, the second TV. In this market, cash in hand talks louder than any credit score.
Time it with your tax refund. Indianapolis lots run their hardest low-deposit pushes in refund season. Your refund can be the deposit and the drive-off money in one check — just do not let the season rush you into the first car you sit in.
Pick up the extra shift. Indianapolis runs on warehouses and logistics, and overtime is real money. A few extra shifts closes a $300 gap faster than any financing trick.
Spending It Right
Shop at least three lots — Pendleton Pike and East Washington Street both make that easy. Compare total price and total of payments, not the biweekly number. Ask if the lot reports to all three credit bureaus, and spend $100 on your own mechanic's inspection: Indiana's lemon law only covers problems reported within 18 months or 18,000 miles of a car's original delivery, so on these cars your inspection is the only warranty you have.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
When every dollar went to the deposit, the driveway stays dark — a lot of Indianapolis buyers street-park on the near east side or in Beech Grove where porch lights do not reach the car. This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day and lights the spot at night — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Recommended · Temu
Insulated Cup Set — 4 Bottles & Cups, Gift Boxed
Coffee stays hot through a whole shift, and the set pays for itself in a week of skipped coffee runs. Four insulated bottles and cups, boxed up nice. 4.5 stars, 89K+ sold.
$5.18 on Temu
See the cup set on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
How much down payment do I need for a car in Indianapolis with bad credit?
Plan on $800 to $1,500 at the in-house lots. Advance Auto Sales advertises deposits as low as $800 plus tax; other lots advertise higher starting points. $500 alone is usually short of driving off, but it is most of the way there.
Can I get a car in Indianapolis with $500 down and bad credit?
Not usually as the full cash to drive off — the advertised deposits start around $800, before tax and fees. Treat $500 as your base, add the tax-and-fees money, and target $800–$1,000 in hand before you shop.
What does a low down payment get me in Indianapolis?
An older, higher-mileage get-to-work car from a lot on Pendleton Pike, East Washington Street, or West 38th Street. More down gets you a better car, a lower payment, and less interest paid over the deal.
Does a bigger down payment lower my payment in Indiana?
Yes — you finance less, so the biweekly payment drops, and you dodge interest on every dollar you put down. On contracts that can run up to the state's 25%-a-year ceiling, that savings is real money.