Low Down Payment Cars in Chicago: What $500 Actually Gets You
Quick answer: $500 to $1,000 down is the real norm at Chicago's bad-credit lots — Chicago-area dealers advertise "$500-$1000 minimum down payment" outright. That money matters more than your credit score. And in Illinois, every used car comes with a mandatory 15-day/500-mile powertrain warranty the dealer can't remove — so your down payment buys a car that's legally protected from day one.
Recommended · Temu
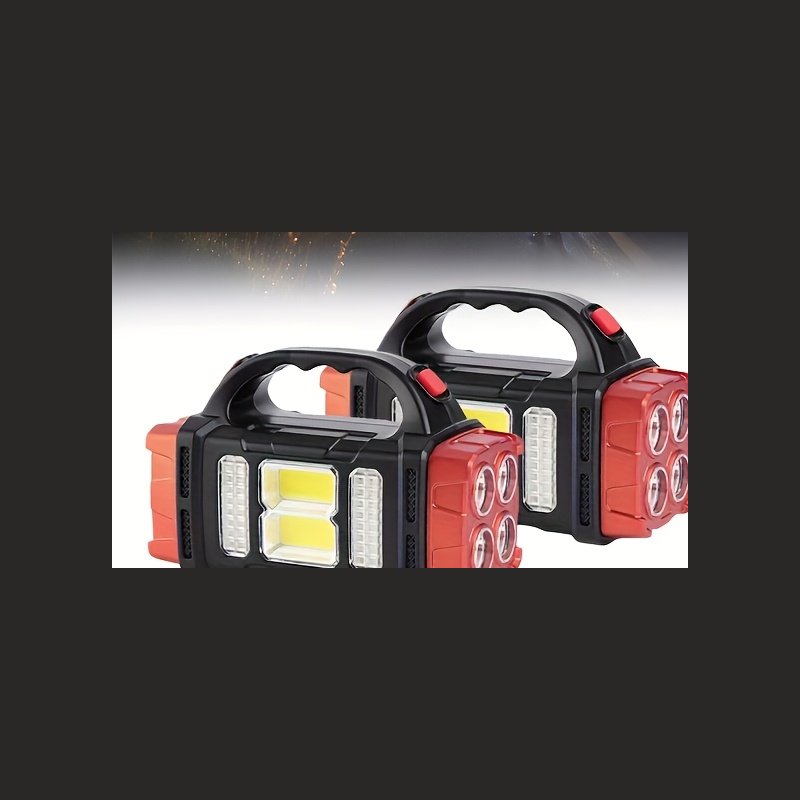
2-Pack Solar LED Lanterns — Buy 1 Get 2
Two solar lanterns for under nine bucks — one for the house, one for the car. They charge in the sun and light up a room when the grid goes down. 4.7 stars, 38K+ sold.
$8.61 on Temu
See the lantern 2-pack on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
Your $500 down in Chicago buys something it buys almost nowhere else: a legal shield. That Illinois 15-day/500-mile powertrain warranty means a dead engine or transmission in the first two weeks gets fixed by the dealer. On a $500-down car — oldest, highest-mileage end of the lot — that shield is worth real money. A transmission job costs more than the whole car. So buy the car and drive it hard for fourteen days.
And the Chicago math that makes the car pay for itself: riding the CTA now costs you $100-plus a month. The day you get the car, that money comes back. So save the $500 to $1,000 firstknowing every month after, the car partly pays for itself.
The Blunt Truth About Down Payments
Everyone obsesses over their credit score. Forget the score. The down payment is what gets you keys.
Here's why. When your credit is wrecked, the dealer's risk is high. Your down payment is the only thing that lowers it. A dealer who won't look at you with zero down will happily shake your hand when you put $800 on the table. Same person, same credit score, same job. The money changed everything.
Chicago-area lots know this game. They advertise it openly — "$500-$1000 minimum down payment, drive today." That's not a slogan. That's the price of admission.

Recommended · Temu
6x4 Ft Brown Outdoor Storage Shed with Lockable Double Doors
Just bought the car? Clear the garage so it actually fits. This weatherproof steel shed has lockable double doors — and no monthly storage-unit bill.
$137.21 on Temu
See the shed on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What $500 Actually Gets You in Chicago
Let's be real about what you're buying.
$500 down gets you in the door at most Chicago in-house lots. You'll be looking at the older end of the inventory — 10 to 15-year-old cars, higher miles, priced around $5,000 to $9,000. It works. It's a car. It gets you to work. But you're picking from the thinner end of the lot.
$1,000 down changes the conversation. Now you're a serious buyer. You get a better pick of cars, sometimes better terms, and the dealer treats you differently. That extra $500 is worth more than it sounds.
$2,000 down and you're in strong shape. Lower amount financed, less interest paid over the life of the loan, and a real cushion against owing more than the car is worth.
Every extra dollar you put down is a dollar you're not paying 20% interest on. On a BHPH loan, that math matters more than anywhere else.
Chicago's Combo: Down Payment Plus Warranty
Here's what makes Chicago different from every other city we've written about.
In most cities, your down payment buys you an as-is car with zero protection. You hand over $800 and drive off praying nothing breaks.
In Illinois, the law forces the dealer to include a 15-day or 500-mile limited powertrain warranty on every used car (815 ILCS 505/2L). The dealer cannot exclude it. Cannot make you waive it. If they try, your whole sale agreement becomes voidable.
So your $500 down doesn't just buy you a car. It buys you a car with a two-week legal shield on the engine and transmission. If the transmission dies on day nine, the dealer has to fix it. That's worth real money — a transmission job costs more than most BHPH down payments.
One rule: if something goes wrong, report it to the dealer within two business days after the warranty period ends. Don't wait. Call, put it in writing, keep proof.

Recommended · Temu
20,000mAh Solar Power Bank — Charges in the Sun
Your phone is your job — the lender's call, the gig app, the map. This 20,000mAh bank tops up from the sun and keeps your phone alive all shift. 4.7 stars.
$4.98 on Temu
See the power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The "No Down Payment" Trap
You'll see ads for zero-down BHPH deals. Here's what the ads don't say.
Most zero-down offers require "approved credit" — tiny print, big catch. If your credit were good enough for approved credit, you wouldn't be shopping BHPH lots. The zero-down pitch is usually fishing for prime buyers, not you.
When a BHPH lot does offer true zero down to bad-credit buyers, the cost moves somewhere else: higher price on the car, higher interest rate, longer term. You're still paying. You're just paying more of it later, with interest.
The honest move: save the $500 to $1,000 first. It opens every door in this city.
Six Real Ways to Raise Your Down Payment Fast
You don't need a miracle. You need a plan.
Sell something. Chicago's Facebook Marketplace moves fast. Old phones, tools, furniture, game consoles. Most people can find $200 to $400 in stuff they're not using.
Pick up weekend work. Day labor, moving help, food delivery. Two or three weekends at $100 a weekend gets you most of the way there.
Bank the tax refund. If it's tax season, don't spend the refund. Park it. That's your down payment and your insurance money.
Cut one subscription, one habit. Streaming services, daily corner-store runs, eating out. $10 a day is $300 a month. That's more than half a down payment.
Ask family — with a plan. Not "can I borrow money." It's "I need $600 for a car down payment, I'll pay you back $150 a month for four months." A plan gets a yes. A vague ask gets a no.
Save the bus fare difference. If you're riding CTA now, you're spending $100+ a month on transit. The day you get the car, that money comes back to you. Think of it as the car paying part of itself.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Protect your car and your driveway. This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges all day and lights up automatically at night — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Recommended · Temu
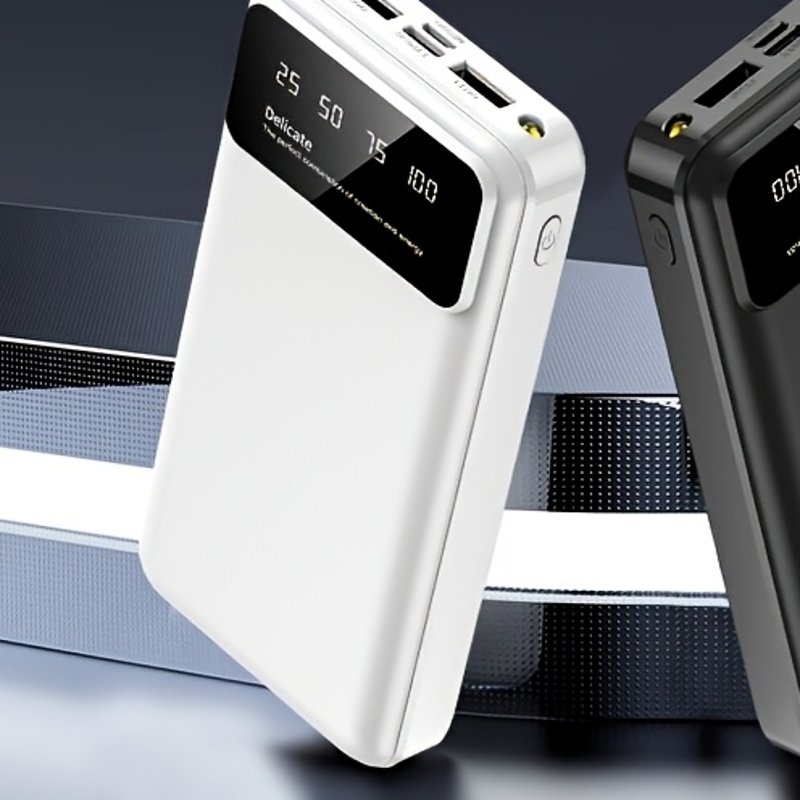
50,000mAh Power Bank — Big Phone Backup Battery
One big battery to keep the family's phones charged through a blackout, a road trip, or a long week away from an outlet. Plain and simple: 50,000mAh. 4.7 stars.
$11.58 on Temu
See the big power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
What's the minimum down payment for a bad credit car loan in Chicago?
$500 to $1,000 is the norm at Chicago-area in-house lots. Chicago dealers advertise "$500-$1000 minimum down payment" outright. More down means better car choices and less interest paid.
Can I get a car with no money down and bad credit in Chicago?
Most zero-down offers require approved credit — which doesn't help if your credit is wrecked. True zero-down BHPH deals exist but cost you more through higher prices and interest. Saving $500 first opens far more doors.
Does Illinois require a warranty on used cars?
Yes. Illinois law (815 ILCS 505/2L) requires dealers to include a 15-day or 500-mile limited powertrain warranty that cannot be disclaimed or waived. Report any defect within two business days after the warranty period ends.
Is a bigger down payment worth it on a high-interest loan?
Absolutely. Every dollar down is a dollar you're not paying 15-25% interest on. On BHPH loans, a bigger down payment is the single fastest way to cut your total cost.