Car Loan After Repossession in Indianapolis: Your Real Options (2026)
Quick answer: A repossession does not end your ability to get a car in Indianapolis — Oak Motors openly advertises financing for buyers with repossessions on their record, because in-house lots lend on income, not history. But know the hard Indiana truth first: this state has no right-to-cure law, so there was no warning before they took it — and there will not be one next time. Your comeback has to be built on a payment you cannot miss.
Recommended · Temu
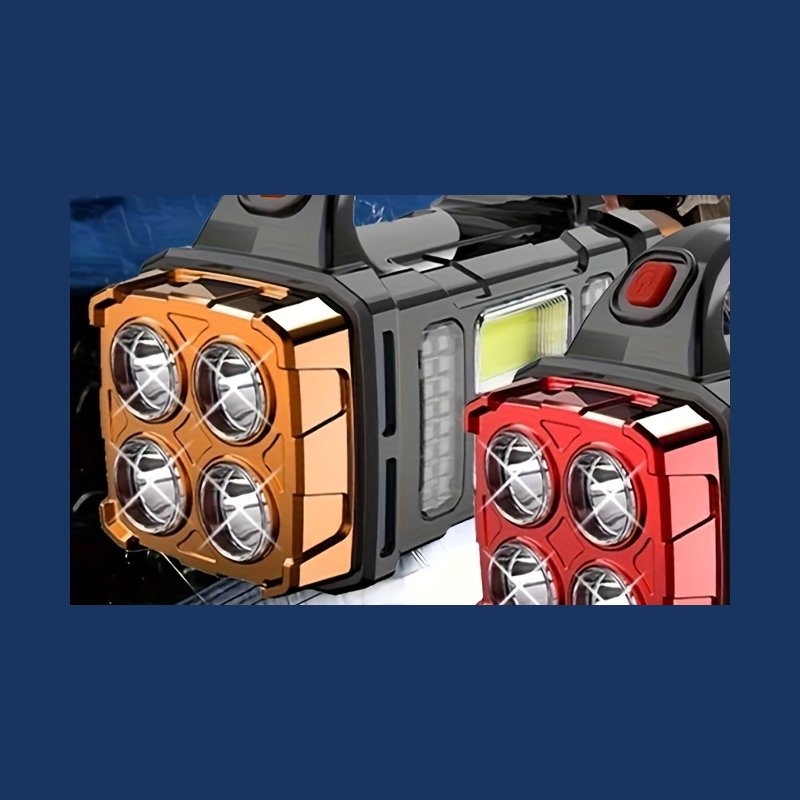
Solar & USB LED Lantern — COB Work Light
When the power goes out, this is your light. It charges from the sun or any USB port — no candles, no wiring, nothing to install. 4.7 stars, 100K+ sold.
$4.94 on Temu
See the lantern on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
Maybe it was gone from the lot when you came out for your shift. The shame is real, and so is the fear nobody will finance you again. Hear me clearly: you are not done. Indianapolis in-house lots approve buyers after a repo every single day. Oak Motors says it right in its own advertising — it finances people with repossessions and even bankruptcy in their past.
But I am not going to sugarcoat the state you live in. Indiana has no cure law — that is why they could take the car without warning you. So the comeback rule here is simple: the next payment has to be boring. Small enough that a bad week or a cut shift cannot break it. A payment on a car you keep beats a bigger one on a car they take again.
It Is Not Over
They took the car. Here is what the fear does not tell you: in Indianapolis, a repo is a chapter, not the book. The lots on Pendleton Pike, East Washington Street, and West 38th Street have seen thousands of repos. Yours does not shock them. What they care about is whether you have a job and money down right now.
Banks will likely say no for years. Fine — the path back runs through in-house financing, and it starts the day you have income and a down payment again.

Recommended · Temu
21V Cordless Drill Kit — Full Tool Set in a Case
Every repair you do yourself is a payment you don't finance. This 21V drill kit comes with the bits and hand tools to start — brakes, batteries, and the small stuff. 4.7 stars, 49K+ sold.
$12.69 on Temu
See the drill kit on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What Indiana Law Actually Does — and Does Not Do
You need this cold.
There is no right to cure in Indiana. Some websites will tell you Indiana lenders must send a notice and give you 10 or 20 days to catch up before a repossession. That describes the law in some other states. It is not Indiana law. Indiana's consumer credit code contains no cure-notice requirement for car loans. If your old contract promised you a notice, that promise mattered — but the statute never did.
The taking needs no warning and no court. A lender can repossess the moment you are in default, without advance notice to you, as long as it is done without a breach of the peace — no force, no threats, no breaking into a locked garage. The one notice Indiana does require goes to somebody else: the repo agent must notify the county sheriff's department before the repossession or within two hours after it.
After the taking, you get a sale notice — and a narrow door. Before the lender sells the car, it must send you written notice of the planned sale. Up until that sale, you can redeem the car by paying the full balance owed plus repo costs. Full balance, not just the missed payments — that is why redemption is out of reach for most people.
You may still owe money after the sale. If the car sells for less than the balance, that deficiency is a debt Indiana lenders can pursue. The state's one limit: on a consumer credit sale with a cash price of $1,000 or less, the buyer is not personally liable for the balance after a repo (IC 24-4.5-5-103). For a car-priced deal, assume the deficiency is real.
Who Approves Post-Repo Buyers in Indianapolis
Oak Motors is the obvious first stop — three Indianapolis lots (West 38th Street, Shadeland Avenue, and South East Street), over 40 years in business, and financing for buyers with repossessions is in their own advertising. Advance Auto Sales, on Pendleton Pike and East Washington Street, decides on income and deposit the same way — advertised deposits start around $800 plus tax.
One question decides whether the new car rebuilds you or just moves you: "Do you report to all three credit bureaus?" Ask it at every lot, and get the answer in writing. On-time payments that actually get reported are how the score climbs back.
Recommended · Temu
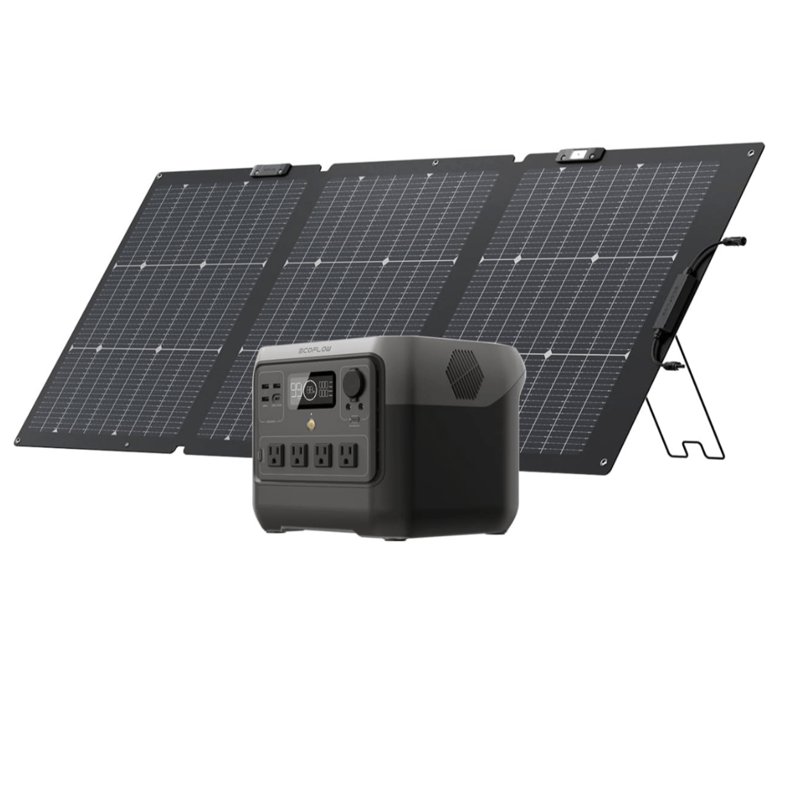
EcoFlow RIVER 2 Pro 700 Portable Power Station (716Wh LiFePO4, 800W AC)
The bigger backup: 716Wh and 800W of AC — enough for a fridge, a TV, or a work laptop through a long outage. Recharges in about 70 minutes. Silent, no fumes, safe indoors.
$327.16 on Temu
See the EcoFlow Pro on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Your Comeback Plan
Know your deficiency situation. If the old car sold short, find out what you owe before you sign anything new.
Save the down payment. $800 to $1,500 puts you in the real conversation at the in-house lots. It talks louder than any explanation.
Bring proof of income like it is your credit score. Because here, it is. Pay stubs, bank statements, proof of address — the full folder.
Choose the payment first, the car second. In a no-cure state, buy the payment you can make in your worst month, not your best one.
The Hope Part
People in Indianapolis come back from repos every day — drivers who lost a car and are driving again, because they changed the math instead of just changing the car. Save the down payment, bring the paperwork, pick the boring payment, and shop the lots that already said yes to people like you. The approval is there. It always was.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
After a repo, the next car matters too much to leave it sitting dark in an apartment lot off West 38th or a south-side street with no lights at all. This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day and lights up when anyone walks up at night — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can I get a car loan in Indianapolis after a repossession?
Yes. Indianapolis buy here pay here lots approve buyers after repossession regularly — Oak Motors advertises financing for buyers with repossessions and bankruptcy on their record. They lend on your current income and down payment, not your history.
Does Indiana have to warn me before repossessing my car?
No. Indiana is not a right-to-cure state — no law requires the lender to notify you or give you time to catch up before the repossession, unless your own contract promises it. The repo agent must notify the county sheriff, but that is not notice to you.
Can I get my car back after a repossession in Indiana?
Only by redeeming it before it is sold — paying the full balance owed plus repossession costs. The lender must send you notice of the planned sale first. There is no Indiana law letting you get it back just by catching up the missed payments.
How long after a repo can I get another car in Indianapolis?
There is no legal waiting period. An in-house lot can approve you as soon as you have steady income and a down payment — around $800 to $1,500 covers the advertised range at Indianapolis lots. Save first, then shop Pendleton Pike and East Washington Street.