Car Loan After Repossession in Kansas City
Quick answer: A repossession in Missouri doesn't end your ability to get a car — Kansas City in-house lots on Truman Road and Independence Avenue approve people after repo every day, because they lend on income, not history. And before that repo, Missouri law owed you a written right-to-cure notice and 20 days to catch up (RSMo 408.554 and 408.555) — if your contract was a Missouri one.

Recommended · Temu
6x4 Ft Brown Outdoor Storage Shed with Lockable Double Doors
Just bought the car? Clear the garage so it actually fits. This weatherproof steel shed has lockable double doors — and no monthly storage-unit bill.
$137.21 on Temu
See the shed on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
Maybe it was early morning in an apartment lot on the east side. Maybe you came out of work in Independence and the car just wasn't there. The shame is real — and so is the fear that nobody will ever finance you again. Kansas City in-house lots approve people after repo every day, because they lend on income, not history. Your down payment and your job matter more than the repo on your record. You're not done. You're starting differently.
Start right: save $500 to $1,000 down — that money talks louder than any apology letter. Then pick a payment you can actually make, not the one your pride wants. And learn the Missouri rule this time: 10 days behind triggers a written notice, and the lender has to wait 20 more days before taking the car. A contract signed across the river in Kansas plays by different rules. Which side of the line you buy on is a legal decision, not just a drive.
It's Not Over
Here's the truth: a repossession is not the end of your car-buying life. The bad-credit lots along East Truman Road and Independence Avenue approve people with repos on their record every day. Auto Bank of Kansas City and Auto Zoom on Truman, El Ranchito Auto Sales on Independence Avenue — these lots have seen your exact situation a thousand times. What they care about is whether you have a job and a down payment right now.

Recommended · Temu
21V Cordless Drill Kit — Full Tool Set in a Case
Every repair you do yourself is a payment you don't finance. This 21V drill kit comes with the bits and hand tools to start — brakes, batteries, and the small stuff. 4.7 stars, 49K+ sold.
$12.69 on Temu
See the drill kit on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What Missouri Law Required Before They Took It
You need to know this — if your loan was a Missouri loan — because Missouri gives you more warning than most states, and because it can matter for what you still owe.
The notice and the 20-day wait. Under RSMo 408.554, after you've been in default for 10 days for failing to make a required payment — and you haven't voluntarily surrendered the car — the lender must send you and every cosigner a written notice of default. It has to state the lender's name, address, and phone number, identify the transaction, state your right to cure, and give the amount now due and the last day for payment. Then, under RSMo 408.555, after a default that is only a missed payment, the lender cannot accelerate the loan — demand the whole balance — or repossess until 20 days after that notice. Tender all the unpaid sums due, plus any delinquency charges, inside that window, and the contract continues as though the default never happened. No proper notice, no clean repo.
The limit nobody tells you. That protection is rationed. Once default on the same loan has happened twice, the lender is no longer bound by the notice-and-wait rule — and the second notice itself warns that a further default means no right to cure. Roughly a month of breathing room on your first two defaults. No guaranteed warning on the third.
After the taking. Before the lender can sell the car, RSMo 400.9-611 requires it to send you a reasonable notification of the disposition, and in a consumer deal that notice must describe any deficiency liability and give you a phone number to learn the redemption amount. Redemption under RSMo 400.9-623 means paying the full payoff plus repossession expenses before the sale — not just catching up missed payments. Read that notice the day it arrives. The clock in it is real.
The deficiency — what you may still owe. If the car sells for less than you owed, Missouri limits the lender's comeback: under RSMo 408.556, a deficiency is recoverable only if the amount financed was more than $500 and the balance unpaid at default was $300 or more, and the lender must show it followed the Article 9 sale rules. After the sale it also owes you an explanation of how the deficiency was calculated. If a lender is chasing you and never sent proper notices, that's worth a call to a Missouri consumer lawyer or the Attorney General's Consumer Protection division.
The Kansas-side warning. All of the above is Missouri law. If your car was bought on State Avenue in Kansas City, Kansas, your deal was under Kansas consumer law, with its own cure rules. Don't assume the Missouri timeline applied — check which state's contract you signed.
What Lenders See After a Repo
A repossession tanks your credit score. There's no sugarcoating it — it's one of the worst marks you can have. A bank won't touch you for years. Subprime lenders will, but at brutal rates and with big down payment demands.
That's why you don't go back to a bank after a repo. You can ask CommunityAmerica Credit Union honestly what you'd qualify for — its First-Time Auto Loan requires no derogatory history, so a fresh repo likely closes that door — but most post-repo buyers here land at an in-house lot. Buy-here-pay-here dealers look at your paycheck and your down payment. The repo is background noise to them.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Your Comeback Plan
Know what you still owe. If there's a deficiency balance from the old car, find out the amount and whether the lender followed the notice rules. Don't sign a new deal blind to an old debt.
Save your down payment. After a repo, $500 to $1,000 down is your ticket back in — around $700 is the median down Kansas City dealers publish. That money talks louder than any apology letter.
Bring proof of income. Pay stubs, bank statements — the works. Your job is your new credit score. Steady income after a repo is the strongest thing you can show a dealer.
Don't repeat the mistake. The repo happened for a reason — usually a payment you couldn't afford. This time, pick a payment you can make on your worst month, not your best one. Buy on the Missouri side if you want Missouri's cure protection, and remember: it runs out after two defaults on the same loan. Spend it like it's scarce, because it is.
People in Kansas City come back from repos every day — the east side, Independence, Raytown, the Northland. The repo was a chapter. It wasn't the book. Save the down payment, bring your income paperwork, and walk Truman Road, Independence Avenue, and North Oak. The approval is there. It always was.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Starting over with a new car in a Kansas City apartment lot or on street parking in Independence? This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day and lights up automatically at night — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
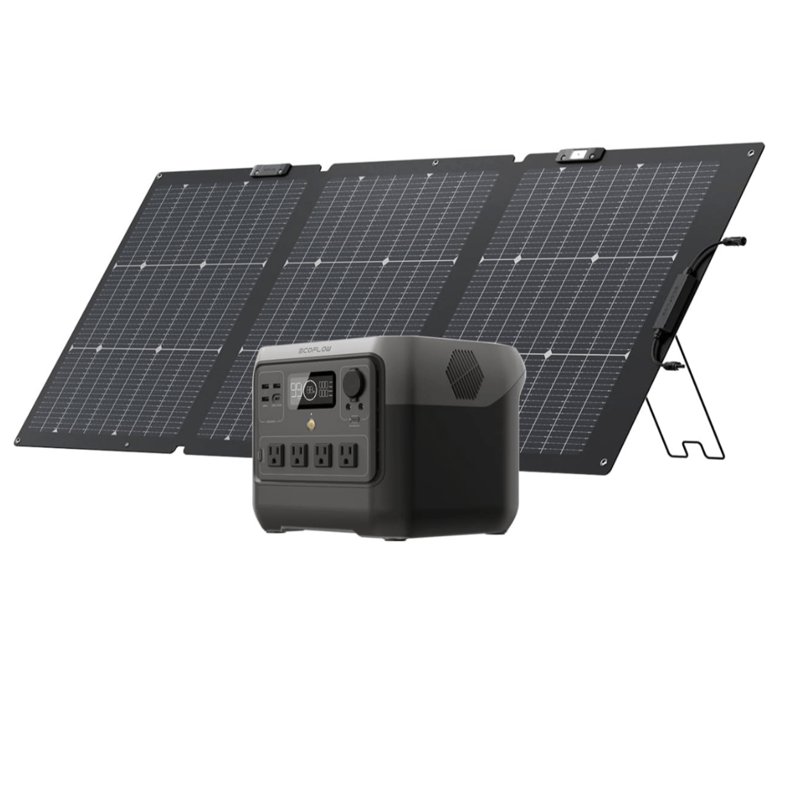
Recommended · Temu
EcoFlow RIVER 2 Pro 700 Portable Power Station (716Wh LiFePO4, 800W AC)
The bigger backup: 716Wh and 800W of AC — enough for a fridge, a TV, or a work laptop through a long outage. Recharges in about 70 minutes. Silent, no fumes, safe indoors.
$327.16 on Temu
See the EcoFlow Pro on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can I get a car loan in Kansas City after a repossession?
Yes. Kansas City buy-here-pay-here lots on Truman Road and Independence Avenue approve buyers after repossession regularly — they lend based on income and down payment, not credit history.
Does Missouri require notice before repossessing a car?
Yes — for a missed-payment default on a Missouri contract. Once you're 10 days in default, the lender must send a written notice of default and right to cure (RSMo 408.554), and it cannot repossess until 20 days after that notice (RSMo 408.555). After two defaults on the same loan, it no longer has to give that notice. Kansas contracts follow Kansas law.
How long after a repo can I get another car in Kansas City?
There's no legal waiting period. In-house lots can approve you as soon as you have income and a down payment. Save $500–$1,000 down, bring proof of steady income, and find out whether you still owe a deficiency on the old car.
Can I still owe money after my car is sold in Missouri?
Yes, that's a deficiency — but Missouri limits it. Under RSMo 408.556, the lender can recover a deficiency only if the amount financed was more than $500 and the unpaid balance at default was $300 or more, and it must show it complied with the sale-notice rules and explain how the amount was calculated.