Low Down Payment Cars in St. Louis
Quick answer: In St. Louis, $500 is the number the ads shout — Affordable Auto Credit on Gravois Avenue advertises buy-here-pay-here downs as low as $500 on approved credit. But "as low as" is doing heavy lifting: some Gravois lots advertise half down instead. Your down payment matters more than your credit score here, so save it, then ask every lot for the total cash to drive off, not the headline number.
Recommended · Temu
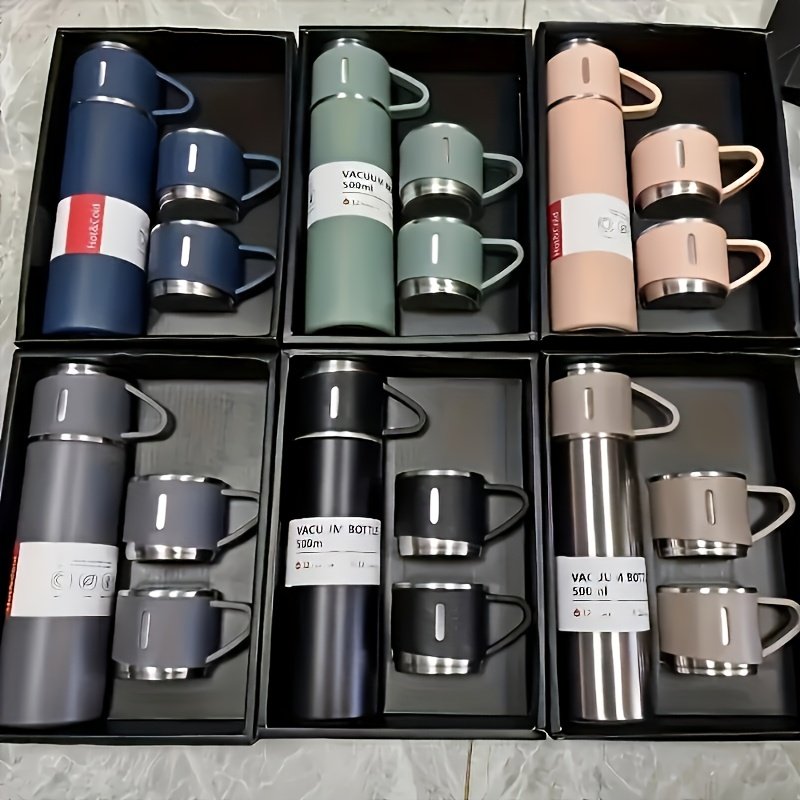
Insulated Cup Set — 4 Bottles & Cups, Gift Boxed
Coffee stays hot through a whole shift, and the set pays for itself in a week of skipped coffee runs. Four insulated bottles and cups, boxed up nice. 4.5 stars, 89K+ sold.
$5.18 on Temu
See the cup set on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
Fifty dollars a week for ten weeks. Skip the eating-out money, skip the weekend money, and in ten weeks you're standing on Gravois Avenue with $500 cash — and $500 cash with a 520 score beats a 620 with empty pockets every time in this city. Dealers don't care about your score. They care about one thing: can you put money down today?
Two rules while you save. Don't borrow the down payment from family — if you can't save $500 yourself, you'll struggle with the weekly payment, and saving it proves to you that this works. And read the ads like a contract, because the gap between "$500 down" and "half down" on the same street is thousands of dollars. The headline gets you on the lot. The math on the actual car is what you pay.
The Down Payment Is the Whole Game
Nobody told you this. Your credit score isn't what's keeping you out of a car. It's the money you hand over at the lot.
Dealers on St. Louis's bad-credit corridors don't care about your 520 score. They care about one thing: can you put money down today? A $500 down payment with a 520 score beats a 620 score with zero dollars in hand. Every time. The down payment is how the dealer protects himself — it's the one thing standing between him and a total loss if you walk away from the car.
That's why the range matters. Affordable Auto Credit at 4568 Gravois Avenue advertises financing starting as low as $500 down on approved credit. A few miles up the same street, Taylor Auto Sales at 3000 Gravois advertises buy here pay here with half down. On a $6,000 car, that's the difference between $500 and $3,000 — same avenue, same week. The real St. Louis range is $500 to half the car, depending on the lot and the car.

Recommended · Temu
6x4 Ft Brown Outdoor Storage Shed with Lockable Double Doors
Just bought the car? Clear the garage so it actually fits. This weatherproof steel shed has lockable double doors — and no monthly storage-unit bill.
$137.21 on Temu
See the shed on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What $500 Actually Gets You
Let's be real. Five hundred dollars down at an in-house lot gets you into an older, higher-mileage car. It's a get-to-work car — the sedan or SUV that gets you from North City to the job in West County, or from South City across the river. It won't be the nicest thing on the lot. Ask what cars on that lot actually go for $500 down before you pick one out in your head.
One thousand dollars down gets you a better pick of the lot and sometimes a lower weekly payment. Every extra hundred gives you leverage — a better car, a better payment, a better deal. But don't wait until you have $3,000 if the lot you want works at $500. The perfect down payment is the enemy of having a car this month.
And watch the difference between down payment and drive-off cash. Taxes, title, and registration are real money in Missouri, and a car registered in the St. Louis area also needs its emissions paperwork in order. Ask one question at every lot: "What is the total cash I hand you today to drive away?" If the answer is bigger than the ad said, you just learned something about that lot.
How to Raise It Fast
Sell what you're not using. Old phones, tools, a TV gathering dust. A buyer in St. Louis with $500 cash in hand beats a buyer with $500 in a savings account he won't touch.
Save $50 a week for 10 weeks. That's it. Ten weeks and you're driving. Skip the eating-out money, skip the weekend money, and in ten weeks you're at the lot.
Ask about your tax refund timing. Lots run their biggest low-down pushes around tax season. If your refund is coming, time your visit for it — and expect the good cars to move fast.
Don't borrow the down payment from family. If you can't save $500, the weekly payment will hurt worse. Save it yourself. It proves to the dealer — and to you — that you can make this work.
Recommended · Temu
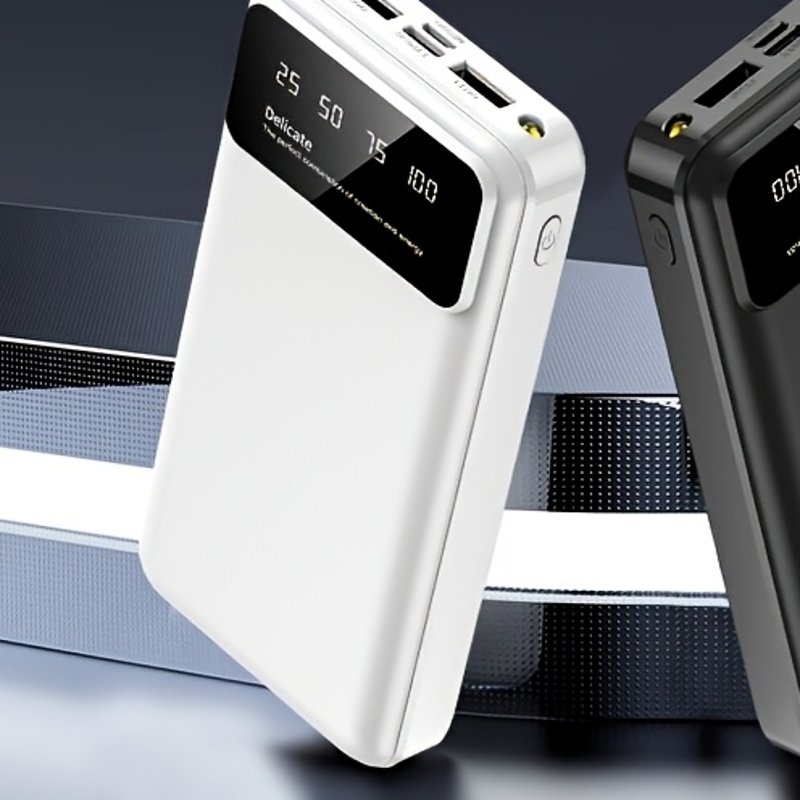
50,000mAh Power Bank — Big Phone Backup Battery
One big battery to keep the family's phones charged through a blackout, a road trip, or a long week away from an outlet. Plain and simple: 50,000mAh. 4.7 stars.
$11.58 on Temu
See the big power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Spending It Right
Once you have the money, don't waste the moment. Work Gravois Avenue in South City, the West Florissant corridor and Pershall Road in North County, and North Lindbergh — Highway 67 — up through Florissant, where Travers GMT Auto Sales and DriveTime of North County sit. Compare at least three lots before you sign anything.
Negotiate the total price, not the weekly payment. Ask two questions before you sign: "Do you report to the credit bureaus?" and "Is this car sold as-is?" In Missouri, used cars can legally be sold as-is — the lemon law covers new vehicles only. And in the St. Louis emissions area, ask for the emissions certificate: a dealer who sells you a car without one owes you a free fix if it fails within 10 days and 1,000 miles.
One last protection to know: Missouri law (RSMo 408.554 and 408.555) says if you fall behind later, the lender must send you a written notice and give you 20 days to cure before it can repossess. A bigger down payment means a smaller balance — and a much smaller chance you ever need that notice.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
When the car you just stretched to buy sits in a driveway in Florissant or a lot in South County with no lighting, this 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day and lights it up at night — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
How much down payment do I need for a car in St. Louis with bad credit?
Plan on $500 to $1,000 at most in-house lots. Affordable Auto Credit on Gravois advertises as low as $500 down on approved credit, while Taylor Auto Sales on the same street advertises half down — so the real answer depends on the lot and the car.
Can I get a car in St. Louis with no down payment and bad credit?
Almost never at a buy-here-pay-here lot. Money down is how these dealers protect themselves. If you see a zero-down pitch, read every line of the contract and ask for the total cash needed to drive off before you sign.
What does $500 down get me in St. Louis?
An older, higher-mileage get-to-work car at a lot that honors that price — not the newest SUV on the front row. More down means a better car, a lower payment, and less interest paid over the life of the loan.
Does a bigger down payment lower my weekly payment?
Yes. The more you put down, the less you finance, which means lower payments and less interest. On a high-interest in-house loan, every extra hundred dollars down saves you real money — and lowers your risk of ever facing a repossession notice.