Can You Buy a Car With Two Repossessions?
Quick answer: Yes, but rarely through a regular subprime lender right away. Credit Acceptance's published guidance says traditional lenders prefer about 12 months after one repo and the wait may extend to 24 months with multiple repos, and Drivers Lane reports most subprime lenders will not lend with more than one repo showing. The near-term path is buy here pay here plus a real down payment, after you settle any deficiency balances you still owe.

Recommended · Temu
6x4 Ft Brown Outdoor Storage Shed with Lockable Double Doors
Just bought the car? Clear the garage so it actually fits. This weatherproof steel shed has lockable double doors — and no monthly storage-unit bill.
$137.21 on Temu
See the shed on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
You have been told no so many times you stopped asking.
One repossession is a story a lender can talk himself into. Two is a pattern — that is how most lenders read it. That is why one-repo advice does not work for you. The doors are narrower, the wait longer, and the order you fix things in matters more.
You are not banned from buying a car. You are shut out of the easy path — most subprime lenders, the lenders built for bad credit, draw their line at one repo. Your near-term path is buy here pay here. Your longer path runs through two debts most buyers do not know they still owe.
This is the two-repo path, in order. For the single-repo version, see a car loan after a repo.
Why do two repossessions hit harder than one?
A lender is not judging your character. He is guessing: will this loan end like the last ones did?
One repo can be explained — a job loss, a divorce, a medical bill. Two reads differently on paper, even if the real story is that the first loss knocked you down and the second car was bought while you were still down.
Drivers Lane puts it bluntly: many subprime lenders may give you the benefit of the doubt with one past repossession, but most will not offer a loan with more than one repo showing.
Your fight is time, settled debts, and money down. In the right order, the second repo stops being the whole file.
How long do you actually have to wait after a second repo?
There is no law that makes you wait. There are only lender rules, and every lender sets his own. Trust the pattern in published lender guidance.
Credit Acceptance, a large subprime lender, publishes this standard: most traditional lenders — banks and credit unions — prefer a full 12 months after a repossession, and with multiple repossessions, that wait may extend to 24 months.
The waiting-period reality:
- Under 6 months since the second repo: Banks, credit unions, and most subprime lenders are a near-certain no. Buy here pay here is the realistic door — those dealers judge income today.
- Around 12 months: One-repo buyers start getting real subprime offers here. With two, most subprime lenders still pass, per Drivers Lane. A few may look if everything since stayed clean, deficiencies are settled, and your down payment is strong — the exception, not the plan.
- Around 24 months: The window Credit Acceptance's guidance points to for multiple repos. Two years of on-time payments, with repo debts cleared, puts you back in the room with real lenders.
- Seven years is not your wait: A repo stays on your report seven years from the first missed payment that led to it, per Credit Acceptance. Lenders weigh how recent the second repo is, and what your file shows since.
Time alone is not enough, though — time with two unpaid repo debts hanging on is wasted time.
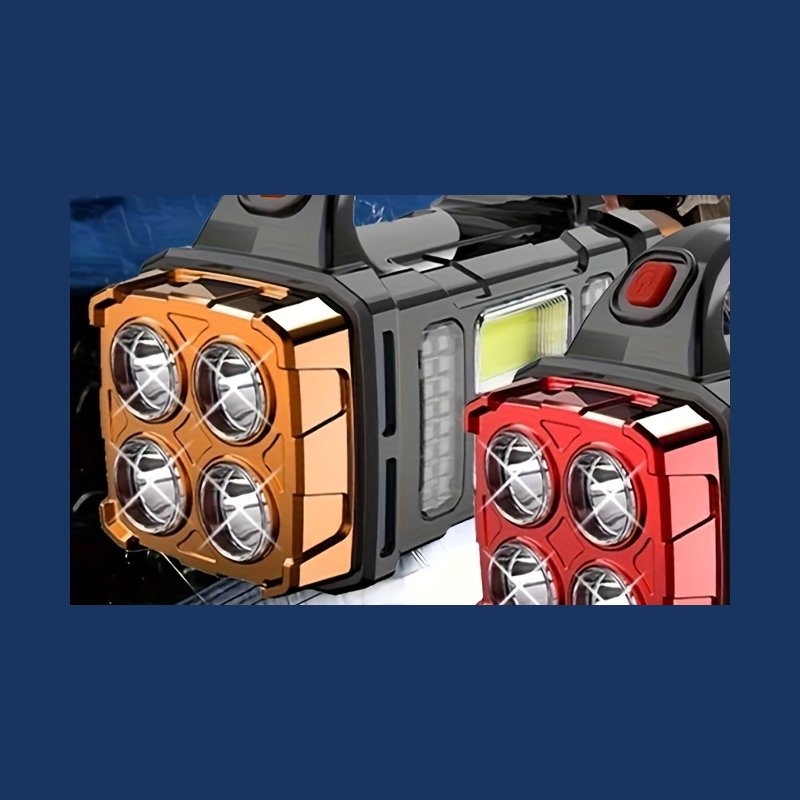
Recommended · Temu
Solar & USB LED Lantern — COB Work Light
When the power goes out, this is your light. It charges from the sun or any USB port — no candles, no wiring, nothing to install. 4.7 stars, 100K+ sold.
$4.94 on Temu
See the lantern on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What is a deficiency balance, and why does it block your next loan?
When a lender takes a car back and sells it, the sale almost never covers what you owed. The difference — what you still owed, plus repossession fees, minus what the car sold for — is a deficiency balance, and you can still owe it after the car is gone. The Consumer Financial Protection Bureau's example: owe $10,000, the car sells for $7,500, you owe $2,500, plus fees.
With two repos, you may have two balances. Our deficiency balance after a repo page covers the mechanics.
It blocks you because a new lender sees an unfinished car debt and thinks: if he did not finish paying for the last car, why fund the next one? Credit Acceptance's guidance agrees — resolving a repo balance improves your chances, and unpaid balances are a red flag.
The settlement sequence, in order:
- Find both balances. Pull your reports. Write down who owns each debt — lender or collector — and the amount claimed.
- Get the number in writing. Balance, sale price, and fees. If a figure looks wrong, ask how the car was sold.
- Negotiate before you apply anywhere. Ask what they will accept to mark it settled or paid, or ask for a payment plan. Get any deal in writing before money moves.
- Keep the proof. Save the agreement and the settled-or-paid letter — your answer when a lender asks, and your evidence if the report shows it open.
Settle first, save second, apply third. Most people do it backwards and burn inquiries at lenders who were never going to say yes.
Why is the down payment the lever that moves everything?
For this reader, the down payment is the whole argument.
Most subprime lenders want 10% down or $1,000, whichever is more. That is the floor for a normal bad-credit buyer — with two repos, it is only where the conversation starts. More down shrinks the loan, so the lender risks less, and shrinks your payment, so you are less likely to fall behind again. It also proves, in cash, that you can save.
Set your number before you shop, using our breakdown of how much down payment you really need. While you save, keep every other bill current. Settled deficiencies plus real money down plus clean payments is a file a lender can defend. Any one missing makes it one he cannot.

Recommended · Temu
1080P Video Doorbell Camera — Wireless, No Drilling
Your car sleeps in the apartment lot. This camera sticks on with no drilling, runs on a battery, and shows your front door — and who is near your car — right on your phone. 4.7 stars, 250K+ sold.
$9.98 on Temu
See the doorbell on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What about buy here pay here — real path or trap?
Both, depending on how you use it.
Buy here pay here means the dealer is also the lender, so no bank behind him says no over two repos. Credit Acceptance's lender comparison lists these dealers as able to approve immediately, based on income, with a high rate likely. Approval turns on proof of income, residence, and down payment — not your score. That is the near-term path when the second repo is fresh:
- The rate will hurt. Experian Q2 2026 put average used-car APRs at 19.10% for subprime (501–600) and 21.62% for deep subprime (300–500). BHPH can cost more, so judge the total paid, not the weekly payment.
- Ask if they report. Many BHPH dealers do not report on-time payments. If yours does not, perfect payments buy a car, not credit recovery.
- Buy less car than they offer. The payment has to survive a bad month. A third repo is what your file cannot absorb.
Used that way, BHPH is a bridge to a regular subprime loan in 12 to 24 months.
What should you do first, starting today?
- Stop applying for a while. Every application at a lender who will not touch two repos is a wasted inquiry.
- List both repos with dates and balances. Who owns each debt, and how much is claimed.
- Settle both deficiencies, in writing, and keep the proof.
- Save past the minimum down payment while paying everything else on time — no new lates.
- If you must drive now, buy through buy here pay here on income, smallest payment that gets you to work, and confirm whether they report.
- If you can wait, aim toward 24 months from the second repo, then apply through subprime dealers, settlement letters in hand.
The no you kept hearing was real — for the wrong lender, at the wrong time, with open debts on the file. Fix the debts, stack the down payment, let the second repo age, and the answer changes. Not to an easy yes. To a yes you can afford.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Your car sits outside overnight — apartment lot, driveway, or street. This 2-pack of solar security lights (3000LM, motion sensor) keeps it lit and watched — no wiring, no electrician, no monthly cost.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
21V Cordless Drill Kit — Full Tool Set in a Case
Every repair you do yourself is a payment you don't finance. This 21V drill kit comes with the bits and hand tools to start — brakes, batteries, and the small stuff. 4.7 stars, 49K+ sold.
$12.69 on Temu
See the drill kit on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can you get a car loan with two repossessions on your credit report?
Yes, but it depends on time and what you still owe. Most subprime lenders will not lend with more than one repo showing, per Drivers Lane, so the immediate path is usually buy here pay here, on income. Regular subprime lenders become realistic around 24 months after the most recent repo, per Credit Acceptance's guidance for multiple repos.
How long after a second repossession should you wait to apply?
Credit Acceptance's guidance says traditional lenders prefer 12 months after one repo, and the wait may extend to 24 months with multiple repos. That is a lender standard, not a law. Buy here pay here dealers may approve much sooner, on income and a down payment.
Do you have to pay off your deficiency balances before buying again?
No law forces you to, but leaving them unpaid hurts twice: they can go to collections, and new lenders treat an unpaid repo balance as a red flag — Credit Acceptance says exactly that. Settling in writing makes your next application much stronger.
How much down payment do you need with two repossessions?
Most subprime lenders want 10% down or $1,000, whichever is more — a floor, not a winning number for a two-repo buyer. More down lowers the lender's risk and your payment, and is often the difference between BHPH-only and a real subprime offer.
<!-- sources: Credit Acceptance, "How Long After a Repo Can You Buy a Car?" (creditacceptance.com/car-buyers/express-lane/financing-after-repo, publisher's own buyer guidance, checked 2026-11-06) — most traditional lenders prefer 12 months after a repo, the wait may extend to 24 months with multiple repossessions, repossession stays on report seven years from first missed payment, resolve deficiency balances (unpaid balances are a red flag for new lenders), lender comparison: traditional bank 12 months or longer, credit union 12-24 months, subprime lender less than 12 months, BHPH immediate and based on income with high rate likely, BHPH/specialty lenders may approve soon after a repo with steady income; Drivers Lane, "Can I Get an Auto Loan After a Repossession?" (driverslane.com, checked 2026-11-06) — "Many subprime lenders may be willing to give you the benefit of the doubt with one past repossession. However, most won't offer you a loan with more than one repo showing on your credit reports," subprime approval weighs income, employment, residence stability, and down payment; CFPB, "What happens if my car is repossessed?" (consumerfinance.gov, checked 2026-11-06) — deficiency balance is the difference between the amount left on the loan plus repossession fees and the sale price, example $10,000 owed / $7,500 sale = $2,500 owed plus fees; Experian Q2 2026 average APRs via SPEC verified data (used: subprime 501-600 19.10%, deep subprime 300-500 21.62%); subprime down-payment standard (10% down or $1,000, whichever is more) via SPEC verified data citing AutoCreditExpress / WSJ BuySide; BHPH approval on income/down payment rather than credit and non-reporting of on-time payments by many dealers — SuperMoney BHPH guide citing CFPB, checked 2026-11-06. No specific deficiency-settlement percentage is stated because no authoritative source verified a standard discount. -->