Low Down Payment Cars in New York City: What $500 Actually Gets You (2026)
Quick answer: In New York City, $500 down is a conversation starter, not a finished deal. The advertised downs on outer-borough lots often start higher — one Queens Village lot advertises $1,500 down on a $7,999 car — and your drive-off cash also has to cover tax, title, registration, plates, and insurance in the most expensive car-owning city in America. Your down payment matters more than your score, but here it has to be real.
Recommended · Temu
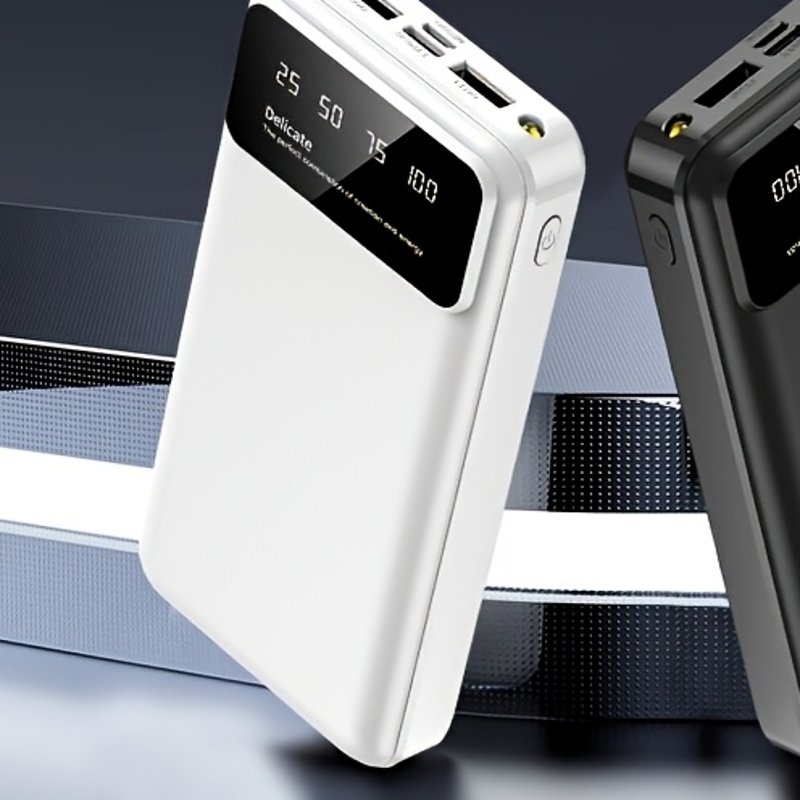
50,000mAh Power Bank — Big Phone Backup Battery
One big battery to keep the family's phones charged through a blackout, a road trip, or a long week away from an outlet. Plain and simple: 50,000mAh. 4.7 stars.
$11.58 on Temu
See the big power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
I'll tell you the New York version of the truth: $500 down with a 520 score still beats $0 down with a 620. Cash talks on Northern Boulevard the same way it talks everywhere. But New York adds a tax nobody warns you about — the cost of simply owning the car here. Insurance in this city is brutal, a garage spot can cost as much as a car payment, and if you're street-parking in the Bronx you're moving the car for alternate-side rules forever.
So don't just save the down payment. Save the down payment plus your first insurance payment plus registration, and be honest about parking. If the numbers say the car eats your whole check, the subway wins and there's no shame in that math. If you're on Staten Island or in Far Rockaway or working a job in the suburbs, the car wins — and then every extra hundred down is leverage.
Down Payment vs. Drive-Off: The Gap That Bites
The number on the windshield banner is never the cash you need. Here's what stacks on top:
The down payment itself. That's the dealer's protection and your approval lever — the money that says you're serious.
Tax, title, registration, plates. New York collects sales tax on the purchase and the DMV takes its cut before you drive anywhere. Budget for it or your $500 magically becomes the whole budget and the deal dies at the desk.
Insurance, first payment, before the car moves. New York requires insurance to register the car, and city insurance premiums are among the highest in the country. Lots will ask to see an insurance card — Hi5Cars in Far Rockaway lists it right in its document checklist, next to your license, utility bill, and pay stubs.
Ask every lot one question: "What is the total cash I hand over today to drive off?" Write that number down. Compare that number, lot to lot.
Recommended · Temu
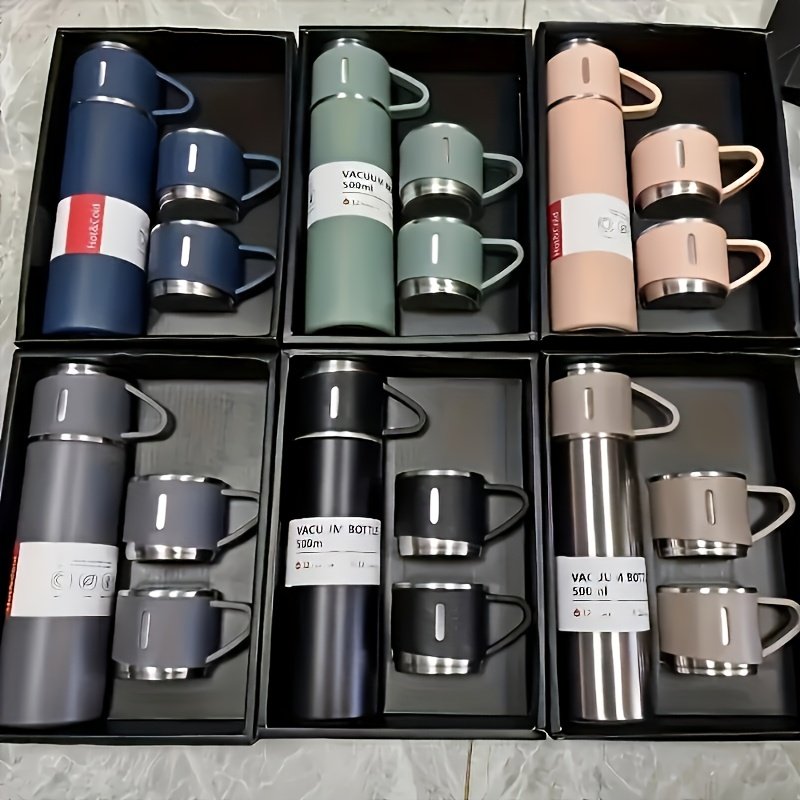
Insulated Cup Set — 4 Bottles & Cups, Gift Boxed
Coffee stays hot through a whole shift, and the set pays for itself in a week of skipped coffee runs. Four insulated bottles and cups, boxed up nice. 4.5 stars, 89K+ sold.
$5.18 on Temu
See the cup set on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
What the Ads Actually Say Here
Real numbers from real city lots, so you can calibrate:
Motor City in Queens Village advertises cars the loud way: a $7,999 Kia advertised at $1,500 down and "as low as $50 a week," with marketing aimed squarely at buyers with repos, bankruptcies, and cash jobs. That's their ad, not a promise — but it shows you the shape of a New York low-down deal: the down payment is real money, and the weekly number is the hook. Fifty a week is $2,600 a year. Do the full math.
Major World in Long Island City stocks cars from around $8,000 across roughly 900 vehicles and advertises approvals for all credit backgrounds. At that price level, a bigger down payment is what keeps the weekly or monthly payment survivable on a subprime rate.
Hi5Cars in Far Rockaway runs in-house financing for challenged credit — the kind of program where the down payment and your pay stubs are the application.
The pattern: $500 might open the door on the oldest car on the lot. $1,000 to $1,500 down is where the real selection starts in this city.
How to Raise It Fast
Save $50 a week for ten weeks and you have $500; twenty weeks, $1,000. Boring, and it works. It also proves to you — before any dealer tests you — that you can carry a weekly payment, because most in-house lots here collect weekly or biweekly.
Sell what's sitting. Phones, tools, the second TV. In this city, also price out anything you're paying to store. Storage units eat down payments.
Use the refund timing. Lots run their hardest low-down pushes around tax season. If a refund is coming, that's your down payment — don't let it evaporate first.
Don't borrow the down payment. If you can't save it, the payment will break you, and in New York a broken payment means a repo with zero warning — this state has no right-to-cure law. The saving is the training.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Spending It Right in This City
Shop the corridors: Northern Boulevard, Atlantic Avenue in Queens and Brooklyn, Hillside Avenue in Jamaica, Beach Channel Drive in Far Rockaway. Compare at least three lots on total drive-off cash and total of payments — never on the weekly number alone.
One New York gift to spend wisely: every dealer-sold used car under 100,000 miles and $1,500 or more must come with the written warranty in the Used Car Lemon Law (General Business Law §198-b) — up to 90 days/4,000 miles on lower-mileage cars. That warranty is worth real money on a cheap car. It's one more reason your down payment goes further at a licensed dealer than in a private cash sale, where you get no warranty at all.
And before you sign, run the parking plan. A car you can't afford to park is a payment you make to the tow pound. Know where it sleeps before you buy it.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
When every dollar went to the down payment, cheap protection matters. This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day and guards your street-parked car at night — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Recommended · Temu
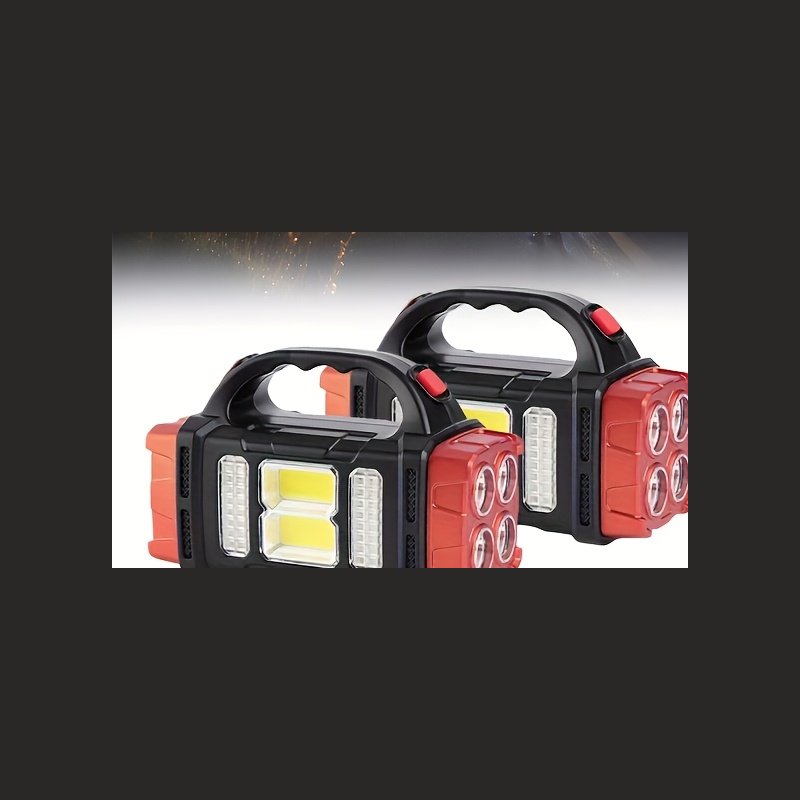
2-Pack Solar LED Lanterns — Buy 1 Get 2
Two solar lanterns for under nine bucks — one for the house, one for the car. They charge in the sun and light up a room when the grid goes down. 4.7 stars, 38K+ sold.
$8.61 on Temu
See the lantern 2-pack on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can I really get a car in New York City with $500 down and bad credit?
Maybe — on the oldest, cheapest car at an in-house lot, with strong pay stubs. But advertised downs in the city often start higher (one Queens Village lot advertises $1,500 down on a $7,999 car), and drive-off cash also has to cover tax, title, registration, and insurance. Bringing $1,000 or more changes the conversation completely.
What's the difference between down payment and drive-off cost in New York?
The down payment goes against the car's price. The drive-off total is everything you hand over that day: down payment plus sales tax, title, registration, plates, and your first insurance payment. In New York City, the gap between the two numbers is where deals fall apart — always ask for the full drive-off figure in writing.
Does a bigger down payment help with bad credit in NYC?
Yes — it's the strongest lever you have. It lowers what you finance, shrinks the payment, and tells the dealer his risk is covered. On a high-rate in-house contract, every extra hundred down also saves you real interest over the life of the deal.
Should I buy from a private seller in New York to save the down payment?
Be careful. New York's used-car lemon law warranty only covers dealer sales — a private sale leaves you with no warranty protection at all. On a cheap car that can break expensively, the dealer's mandatory warranty is often worth more than the private-sale discount.