Bad Credit Auto Loans in Austin: Where to Get Approved in 2026
Quick answer: Yes, you can get a car loan in Austin with bad credit. Get a written preapproval first — from a local credit union like UFCU or Austin Telco if you're a member, or an online subprime lender — then shop the I-35 corridor with it in hand. Plan on 10% down or $1,000, whichever is more, and a used-car APR in the high teens to low 20s at subprime credit (Experian Q2 2026). Buy-here-pay-here is the safety net, not the first stop.

Recommended · Temu
21V Cordless Drill Kit — Full Tool Set in a Case
Every repair you do yourself is a payment you don't finance. This 21V drill kit comes with the bits and hand tools to start — brakes, batteries, and the small stuff. 4.7 stars, 49K+ sold.
$12.69 on Temu
See the drill kit on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Nobody told you this, and it's going to sound strange.
Your bad credit is not the problem. The problem is where you asked.
Walk into a finance office off I-35 with a 560 score and no plan, and you'll get the shrug and the offer you can't afford. But that same 560, carried into the right Austin lender first, can come back with a written preapproval you can take to any lot in Travis County. The score didn't change. The room did.
Mike's take
That line up there is the most important sentence on this page. I spent years thinking my score was a verdict on me. It's not. It's just a number, and numbers can be worked around in the right room. Without a preapproval, you're asking for a favor. With one, you're a buyer with money, and the dealer has to compete for you.
Why Austin makes this urgent
Austin runs on I-35, and I-35 runs slow. If your shift is in South Austin and your rent is in Pflugerville, no version of your week works without a car.
CapMetro is real, but it doesn't cover the map most working people live on. Its tax-funded service area is basically Austin plus a few small member cities like Leander and Manor. Pflugerville and Cedar Park are not member cities and don't get regular service, Round Rock only gets limited contract routes, and San Marcos — growing fast down I-35 — is outside the system entirely.
Translation: in Austin, the car isn't a luxury. It's the job. The real question isn't "can I get a loan with bad credit" — it's "how do I get financed without getting played." The answer is preparation, not hope.
Recommended · Temu
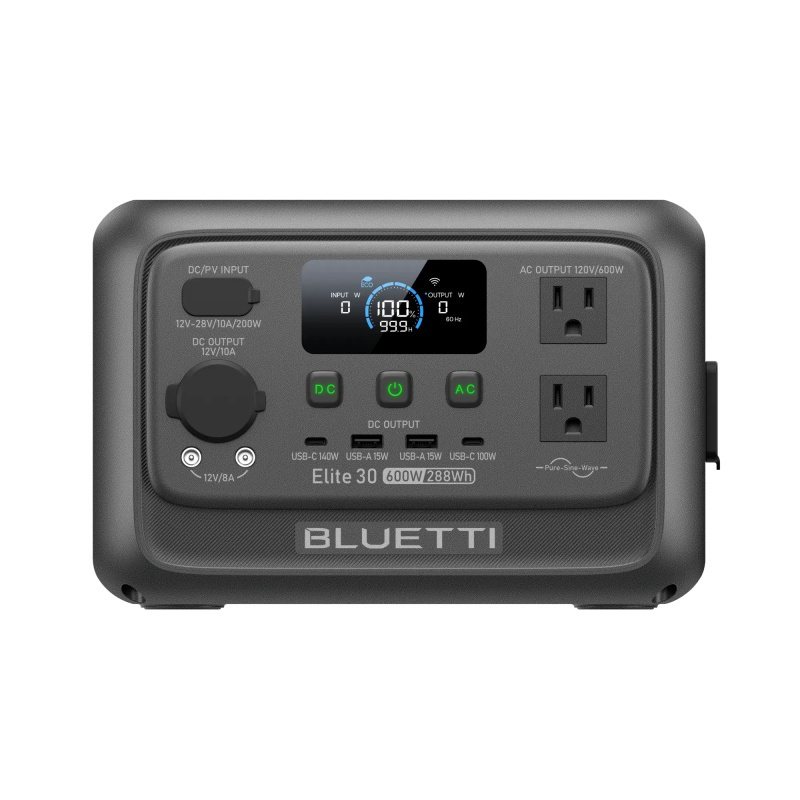
BLUETTI Elite 30 V2 Solar Generator (288Wh LiFePO4, 600W AC)
The step-up pick: 288Wh and a full 600W of AC — enough for a mini-fridge, a CPAP, a laptop or the TV through a long outage. Still silent, still apartment-safe, and it can recharge from a solar panel.
$269.95 on Temu
See the Bluetti on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Where Austin buyers actually get approved
Start online, before any lot. An online subprime preapproval gives you a spending ceiling, an APR to beat, and a total of payments to compare. Now the dealer has to compete against financing you already have.
Then call the two big local credit unions. Credit unions are member-owned and underwrite real people, not just scores — but you have to join first, so check eligibility first.
- University Federal Credit Union (UFCU), Austin's big hometown credit union, finances new and used cars for members. Its published rate sheet prices loans in tiers running down through "Fair," "Marginal," and "Low / No score" — no guarantee at the bottom, but a real price for imperfect credit instead of a closed door. Bring strong income proof.
- Austin Telco Federal Credit Union has served the Austin area since 1941 and makes new, used, and refinance auto loans to members, from Georgetown to San Marcos. Its best advertised rates are for its best-credit members — ask what tier your file lands in.
Franchise dealers on I-35 are the middle path. Stores like Henna Chevrolet at 8805 IH-35 North run used inventory through a finance department that works with many lenders at once. With a preapproval, it's one more bidder. Without one, it's the room where you get played.
Buy-here-pay-here is the safety net. When the lot is also the lender, approval rides on income and down payment, not your score:
- Texas Auto Center, 6809 I-35 South — a BHPH dealer whose own site says it reports monthly payments to the major credit bureaus, with down payments typically 10% to 20%. Reporting matters: a loan that reports can rebuild you; one that doesn't is just expensive debt.
- SFG Auto, 8203 Bluff Springs Rd — a family-owned South Austin lot advertising financing for all credit — "good, bad or none" — with low down payments and clean titles.
BHPH is still the most expensive path: last resort, not first stop. The same Texas playbook we lay out for Dallas and Houston applies here.
The real obstacle: your down payment
Let's say the quiet part out loud: your score is not what stops you. The cash is.
Most subprime lenders want 10% down or $1,000, whichever is more. On a $12,000 used car, that's $1,200 before tax — and Texas adds 6.25% motor vehicle sales tax on top, so the true number is bigger than the sticker suggests. Every extra $500 lowers the payment, lowers the total interest, and makes a lender say yes. If you're short, read how much down payment you actually need and run your own numbers on the bad credit down payment calculator before a salesman runs his.
Here's the rate reality, from Experian's Q2 2026 data — average used-car APRs by band:
- Near prime (601–660): 13.93%
- Subprime (501–600): 19.10%
- Deep subprime (300–500): 21.62%
One Texas protection worth knowing: a dealer-written contract is a retail installment contract under Chapter 348 of the Texas Finance Code, and the state Office of Consumer Credit Commissioner (OCCC) publishes a maximum-rate chart for it. For older used cars, the ceiling works out to roughly 25–27% APR depending on term — high, but not unlimited. If a dealer's rate pushes past that, stop and ask questions. And judge every offer by the total of payments, never the monthly payment alone. A "low payment" stretched over 72 months on a 10-year-old car is how people end up owing money on a car that's already dead.

Recommended · Temu
1080P Video Doorbell Camera — Wireless, No Drilling
Your car sleeps in the apartment lot. This camera sticks on with no drilling, runs on a battery, and shows your front door — and who is near your car — right on your phone. 4.7 stars, 250K+ sold.
$9.98 on Temu
See the doorbell on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Austin checks before you sign
The emissions test is still real here. Texas ended annual safety inspections on January 1, 2025 — but Travis and Williamson are two of the 17 counties where emissions testing stayed. A gasoline car 2 to 24 years old registered in either county must pass one (maximum station charge $11.50) before registration or renewal. A car that can't pass can't be registered to you. Make the seller prove it passes.
No safety inspection means nobody checks the car for you anymore. The state used to catch bald tires and dead brakes once a year. Now it doesn't. Pay for an independent mechanic's inspection — brakes, tires, suspension — before you sign.
Test the AC like it's August. Austin heat and humidity kill the same three things every summer: the air conditioning, the battery, and the cooling system. Run the AC at full blast for the whole test drive. A weak compressor or tired battery is an expensive surprise — and on a subprime budget, that's a missed payment waiting to happen.
Ask the flood question out loud. Central Texas is Flash Flood Alley, and Austin drivers know the low-water crossings that close every hard rain — the city tracks them at ATXFloods.com for a reason. Check the title history and ask directly whether the car has ever been in high water. A flooded car can look clean and die electrically for a year.
Know the repo rule before you're in it. In Texas, once you're in default, a lender can repossess without a court order and without warning first — the one hard limit is that the repo can't "breach the peace": no force, no threats, no breaking into a locked garage (Texas Business & Commerce Code §9.609). Any grace period is whatever your contract says. That's why the payment must fit your worst month, not your best.
Red flags on any Austin lot
- They won't put the APR and total of payments in writing. Texas dealers who finance or arrange financing are licensed and regulated by the OCCC under Chapter 348. A lot that hides the paper is one you walk away from.
- "Guaranteed approval" with no talk of price, rate, or term. Approval is easy. The contract is where you get hurt.
- The payment fits, but the term is 72 months on an old, high-mile car. You'll owe longer than it runs.
- Add-ons you didn't ask for — service contracts, protection packages, fees — quietly stacked into the amount financed. Every line item is removable before you sign, and much harder after.
- They rush your paperwork. Never sign a contract you haven't read in full.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Austin cars live outside — apartment lots off Riverside, driveways in Pflugerville, street parking in Round Rock. This 2-pack of solar security lights (3000LM, motion sensor) keeps yours lit and watched overnight — no wiring, no electrician, no monthly cost.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Recommended · Temu
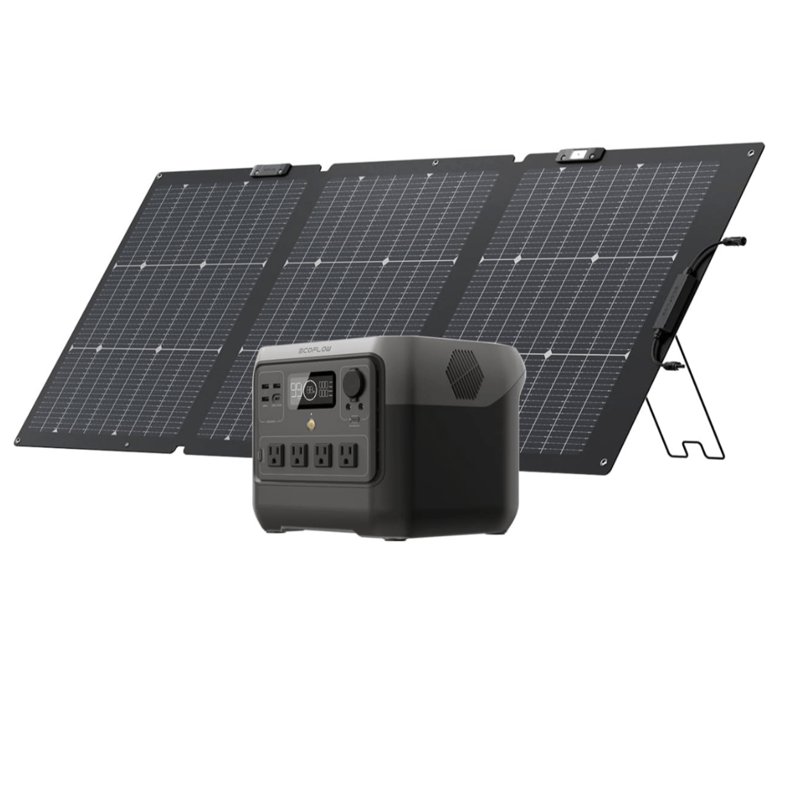
EcoFlow RIVER 2 Pro 700 Portable Power Station (716Wh LiFePO4, 800W AC)
The bigger backup: 716Wh and 800W of AC — enough for a fridge, a TV, or a work laptop through a long outage. Recharges in about 70 minutes. Silent, no fumes, safe indoors.
$327.16 on Temu
See the EcoFlow Pro on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can I get a car loan in Austin with a 500 credit score?
Yes — subprime lenders approve 500-range scores in Austin daily. Expect a used-car APR around the low 20s (Experian Q2 2026 puts the deep-subprime average at 21.62%), a down payment of at least 10% or $1,000, and a smaller, older car than you pictured.
Do Austin buy-here-pay-here lots report to the credit bureaus?
Some do and some don't — ask before you sign. Texas Auto Center states on its own site that it reports monthly payments to the major credit bureaus, so on-time payments there can rebuild your score. If a lot doesn't report, they help nobody but the lot.
Do I still need a state inspection in Travis County in 2026?
Not the old safety inspection — Texas ended that on January 1, 2025. But Travis and Williamson counties still require an annual emissions test for gasoline vehicles 2 to 24 years old, and you can't renew registration without passing it. Maximum station charge in those counties: $11.50.
Can I get approved on gig income — Uber, DoorDash, delivery apps?
Usually, yes, if you can document it. Lenders who work with gig buyers want steady deposits — bank statements and app earnings records instead of pay stubs. Bring several months of statements.
I live in Round Rock or Pflugerville. Does anything change?
Two things. You're likely registering in Williamson County, which has the same emissions-test requirement as Travis. And you're outside CapMetro's regular service area, so budget for the longer I-35 commute — gas, tolls, and a repair reserve — because a breakdown up there is not a bus ride, it's a missed shift.
<!-- sources: Texas Auto Center financing page and FAQ (texasautocenter.com / texasautocenter.net) — 6809 I-35 South, Austin TX 78744; reports monthly payments to major credit bureaus; down payments typically 10–20%. SFG Auto (sfgauto.com via dealer listings) — 8203 Bluff Springs Rd, Austin TX 78744; "easy financing for all credit—good, bad or none," low down payments, clean-title vehicles. Henna Chevrolet (henna.com) — 8805 IH-35 N, Austin TX 78753, new/used dealership. UFCU auto loans page (ufcu.org) — finances new/used vehicles for members; published rate tiers include Fair, Marginal, and Low/No score bands (no specific bad-credit rate quoted in article). Austin Telco FCU auto loans page (atfcu.org) — serving Austin area since 1941; new/used/refinance auto loans for members, branches Georgetown to San Marcos; best-tier rates not presented as subprime rates. Texas DPS, HB 3297 / Vehicle Safety Inspection Program changes (dps.texas.gov) — safety inspections for non-commercial vehicles eliminated Jan 1, 2025; emissions tests still required in 17 counties including Travis and Williamson; DPS cost page: emissions-only maximum $11.50 in Travis/Williamson; DPS inspection criteria: gasoline vehicles 2–24 years old get OBDII test. Texas Comptroller (comptroller.texas.gov) — motor vehicle sales tax 6.25% of sales price. OCCC Current Motor Vehicle Rate Chart, effective Jan 1–Dec 31, 2026 (occc.texas.gov) — Texas Finance Code §348.104 add-on rate ceilings; Class 3 ($12.50) ≈ 21–22.5% APR and Class 4 ($15) ≈ 24.7–26.75% APR equivalent by term; §348.105 alternative 18%. OCCC enforcement materials — Chapter 348 licensing of motor vehicle retail sellers/holders. Texas Business & Commerce Code §9.609 (via Texas Legislature summaries) — self-help repossession after default without court order, no breach of the peace, no statutory advance notice. CapMetro quadrennial performance audit (capmetro.org) — member jurisdictions Austin, Jonestown, Lago Vista, Leander, Manor, Point Venture, San Leanna; CapMetro does not collect tax from / does not provide regular service to Cedar Park and Pflugerville; Round Rock and others served only via contract/interlocal agreements. City of Austin flooding pages (austintexas.gov) — Central Texas is Flash Flood Alley; low-water crossings; ATXFloods.com road closures. Experian Q2 2026 average APR table and 10%/$1,000 down norm per SPEC (verified 2026-10-05). CUT / CORRECTED: the assignment brief said Texas has "no statutory rate cap for used-car RICs" — verification against the OCCC 2026 rate chart and Finance Code §348.104 shows there IS a ceiling (add-on based, ≈25–27% APR equivalent for the oldest used class), so the article states the verified version instead. CUT: specific UFCU/Austin Telco APR figures for bad-credit tiers beyond UFCU's published tier names — not presented as subprime quotes. CUT: any claim that Henna Chevrolet runs a dedicated bad-credit program — verified only as an IH-35 N franchise dealer with used inventory and a multi-lender finance department. -->