Buy Here Pay Here With No Down Payment: What Nobody Tells You
Quick answer: A few buy-here-pay-here lots advertise zero-down deals, but they're rare — and the down payment doesn't disappear, it just moves into your loan. With $0 down, you finance the full price plus taxes and fees, which means you owe more than the car is worth from day one and you pay more interest over the life of the loan. If you can scrape together even $500, it changes the math in your favor.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The Blunt Truth About Zero Down
Here's what nobody tells you about "no money down" at a buy-here-pay-here lot: the dealer isn't giving you a gift. They're just moving numbers around.
Say the car is $8,000. Normal deal: you put $1,500 down, you finance $6,500. Zero-down deal: you finance the whole $8,000 — plus taxes, title, registration, and whatever fees they stack on, let's call it another $1,000. Now you're borrowing $9,000 on a car worth $8,000.
You're underwater before you turn the key. And at 20% interest over four years, that $9,000 loan costs you about $12,700 in payments. Add it up and you've paid nearly $12,700 for an $8,000 car — with zero equity to show for most of the loan.
That's the real price of "no money down." It's not free. It's the most expensive way to buy the car.
Why Dealers Want a Down Payment (It's Not Greed)
It's tempting to think the down payment is just the dealer squeezing you. It's not — or at least, not only that.
A down payment does something no credit score can do: it proves you're serious with cash, not words. Anyone can say they'll make payments. Someone who hands over $1,500 on day one has skin in the game. Dealers have been burned enough times to know the difference.
It also shrinks the loan, which shrinks the monthly payment, which makes it more likely you actually finish paying. A dealer would rather sell you a car you'll pay off than repossess one you can't afford. The down payment protects both of you.
When a lot offers zero down, they're taking on all the risk — and they price for it. Higher rate, longer term, or a cheaper car than you'd get with money down. The risk doesn't vanish. It just shows up somewhere else in the deal.

Recommended · Temu
20,000mAh Solar Power Bank — Charges in the Sun
Your phone is your job — the lender's call, the gig app, the map. This 20,000mAh bank tops up from the sun and keeps your phone alive all shift. 4.7 stars.
$4.98 on Temu
See the power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
When Zero Down Actually Makes Sense
There are real situations where zero down is the right call:
You need the car to earn the money. If the car gets you to a job that pays for the car, waiting three months to save a down payment costs you three months of income. Do the math on that before you decide waiting is "responsible."
You have the down payment money but need it for something else. First month's rent, a security deposit, keeping the lights on — sometimes the $1,000 is doing a more important job elsewhere. That's a legitimate call.
The terms are genuinely reasonable. Rare, but it happens — usually on cheaper cars where the dealer's risk is small. If the total cost looks fair, zero down isn't a trap. It's just a structure.
The key question isn't "is zero down bad." It's "what's the total cost, and can I live with it?" Run that math every time.
How to Make $500 Work Like $2,000
If zero is what you have, here's how to get the most out of a small down payment:
Pick a cheaper car. $500 down on a $6,000 car is a much stronger position than $500 down on a $12,000 car. The down payment is a percentage game — make the percentage bigger by shrinking the price.
Ask about the out-the-door number, not the down payment. Some lots will take $500 down but stack $800 in fees on top. Your real day-one cost is what matters. Get it itemized.
Shorter term beats lower payment. If you can handle $280 a month for 3 years instead of $220 for 4 years, you'll save over a thousand dollars in interest. The dealer will push the longer term because the payment looks smaller. Don't fall for it.
Bring everything else strong. Solid pay stubs, steady job, proof of address, references ready to go. When the money is light, the paperwork has to be heavy.
Recommended · Temu
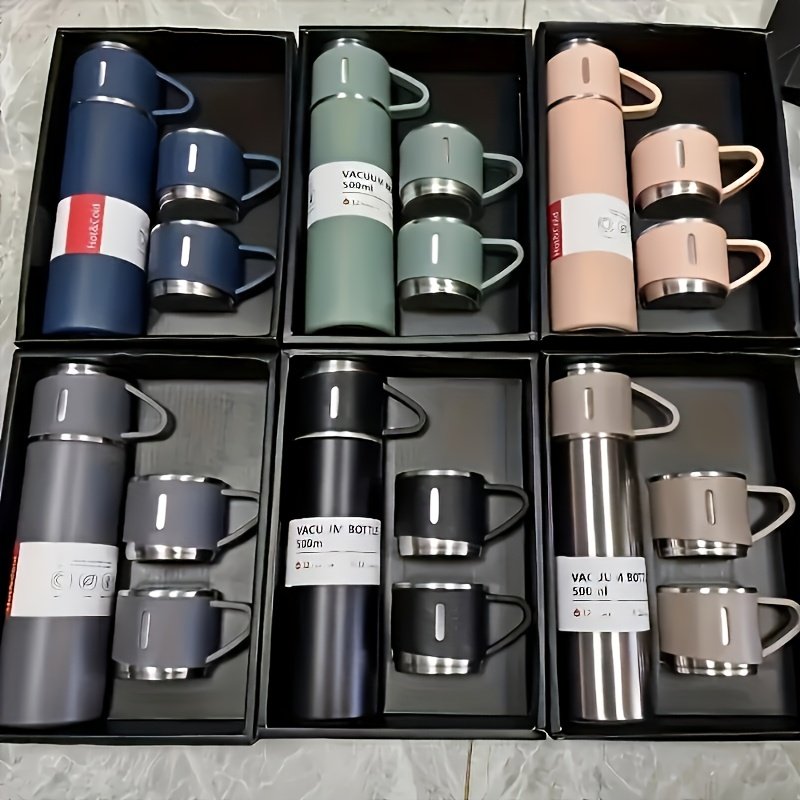
Insulated Cup Set — 4 Bottles & Cups, Gift Boxed
Coffee stays hot through a whole shift, and the set pays for itself in a week of skipped coffee runs. Four insulated bottles and cups, boxed up nice. 4.5 stars, 89K+ sold.
$5.18 on Temu
See the cup set on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
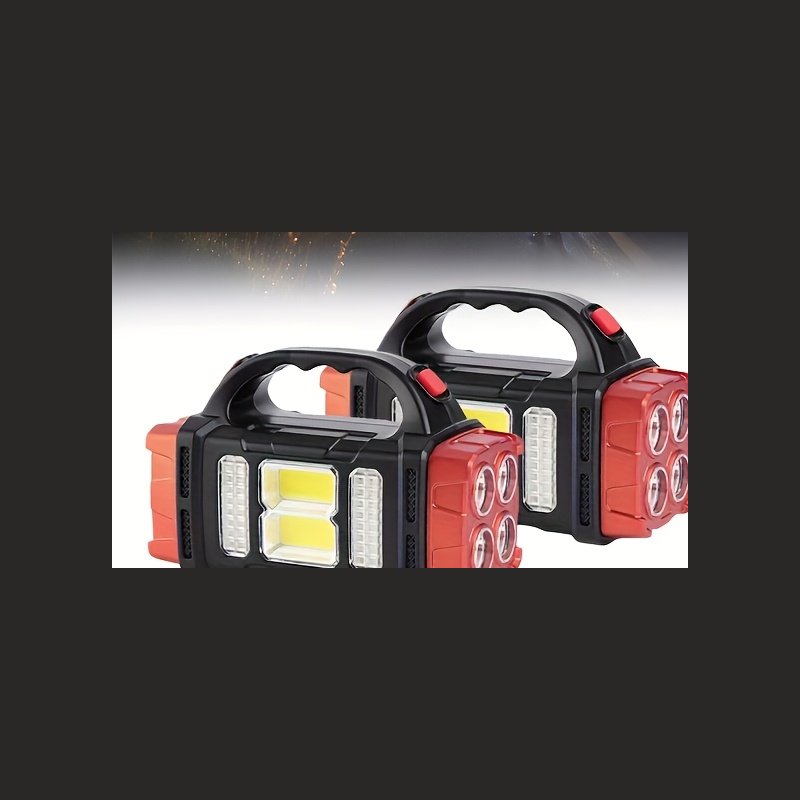
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Every dollar counts when you're saving for a down payment. This 2-pack of solar security lights (3000LM, motion sensor) protects your car for under $20 — no wiring, no electrician, no monthly cost.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Recommended · Temu
2-Pack Solar LED Lanterns — Buy 1 Get 2
Two solar lanterns for under nine bucks — one for the house, one for the car. They charge in the sun and light up a room when the grid goes down. 4.7 stars, 38K+ sold.
$8.61 on Temu
See the lantern 2-pack on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can you really get a car with $0 down and bad credit?
Sometimes, at buy-here-pay-here lots — but it's uncommon and it costs you. You'll finance the full price plus taxes and fees, start underwater, and pay significantly more interest. It's possible, just expensive. Always compare the total cost against waiting and saving even a few hundred dollars.
Why do dealers want a down payment so badly?
Because it proves commitment and shrinks their risk in one move. A buyer who puts cash down is statistically far more likely to finish paying. It's the single strongest signal you can send a dealer, stronger than any credit score.
What happens to taxes and fees with zero down?
They get rolled into the loan. On an $8,000 car, taxes, title, registration, and dealer fees can easily add $800 to $1,200 — all financed at the same high interest rate. That's why zero-down loans go underwater so fast.
Is zero down ever the smart move?
Yes — when the car unlocks income you don't have without it. If wheels mean a paycheck, the math favors moving now. Just go in knowing the true total cost, keep the term as short as you can handle, and plan to pay extra toward the principal when you can.