Bad Credit Car Loans in Washington DC
Quick answer: You can get a car loan in Washington DC with bad credit, but be honest about the map: most of the lots that will approve you sit just across the line in Maryland — Suitland, Temple Hills, and District Heights. Your income and your down payment do the approving, not your score. And DC caps the finance charge on a DC retail installment contract at 28.33% for the oldest used cars.

Recommended · Temu
20,000mAh Solar Power Bank — Charges in the Sun
Your phone is your job — the lender's call, the gig app, the map. This 20,000mAh bank tops up from the sun and keeps your phone alive all shift. 4.7 stars.
$4.98 on Temu
See the power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
Here's the blunt truth nobody at a DC franchise store will say out loud: the District itself barely has bad-credit lots. The lots that live on buyers with wrecked credit moved where the rent is cheap — Prince George's County, Maryland, ten minutes across the line. If you live in DC and your credit is shot, your car almost certainly comes from Maryland. That's not a defeat. That's just the map.
The trap is letting the border confuse you. The lot is in Maryland, but you live in DC — so you still title and register the car in DC, through DC DMV, with DC insurance. Know which rules are whose before you sign. Job, down payment, paperwork. That's the whole game.
The Border Is the Story Here
Plenty of jobs DC residents actually hold — warehouses, hospitals, job sites across Prince George's County — are places no bus route serves on a night-shift schedule. If your shift starts at 5 a.m. in Landover, you need a car. Period.
So you shop where the bad-credit inventory actually is: Saint Barnabas Road in Temple Hills, Marlboro Pike in District Heights, and Old Silver Hill Road in Suitland — and at Easterns Automotive Group, which has run on the slogan "Where Your Job is Your Credit" since 1988 and has a Temple Hills location on Saint Barnabas Road. Your paycheck is the application. Your score is background noise.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Where Approval Actually Comes From
Three doors, and you should try them in this order.
Door one: a credit union, before any lot. DC Credit Union is open to people who live, work, worship, or attend school in DC or Prince George's County, and it makes auto loans on new and used cars. Its pre-approval is good for 60 days, so you can walk onto a Maryland lot already knowing your number. Try this door first, even if you expect a no. A no here costs you nothing.
Door two: subprime lenders through regular dealers. Bigger used-car stores in the Maryland suburbs work with lenders who specialize in bad credit. The rate will be ugly, but the loan usually reports to the credit bureaus — which is how your score actually heals.
Door three: buy here pay here. The dealer is the bank. JV Auto Sales on Old Silver Hill Road in Suitland advertises buy here pay here financing, and AMKO Auto on Marlboro Pike in District Heights advertises that it pre-approves buyers regardless of credit. These lots approve on income and down payment. Some report your payments and some don't — ask, and get the answer in writing.
What the Paperwork Actually Looks Like
Forget the score. Here's what gets checked:
Your income. Pay stubs or bank statements showing steady money coming in. A job you've held is worth more than 100 points on your score.
Your down payment. This is the real gatekeeper. AMKO advertises down payments as low as $750 in its listings. Read the fine print in those same listings, though — AMKO also discloses a one-time $1,895 operation cost fee on its cars. The down payment on the sign is never the whole cash number. Ask every lot: "What is my total cash to drive off today?" and make them add it up in front of you.
Your DC life. Proof you live in DC, references, a license or ID. And remember: a car housed and operated in DC must be registered in DC. DC DMV requires the car to pass DC inspection and carry DC insurance, and new DC residents get 60 days to register. If a Maryland lot offers to "just keep the Maryland tags," walk away — that's your ticket and your impound, not theirs.

Recommended · Temu
21V Cordless Drill Kit — Full Tool Set in a Case
Every repair you do yourself is a payment you don't finance. This 21V drill kit comes with the bits and hand tools to start — brakes, batteries, and the small stuff. 4.7 stars, 49K+ sold.
$12.69 on Temu
See the drill kit on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The DC Rules Worth Knowing
DC law caps finance charges on a retail installment contract made in the District. Under D.C. Code § 50-602, the maximum runs from 21.5% on the newest cars up to 28.33% on the oldest used cars — the class most bad-credit buyers land in. One honest warning: that cap covers DC contracts. A contract signed at a Maryland lot is a Maryland contract. Ask which state's law your paperwork is under before you sign, not after.
DC also gives used-car buyers a disclosure right — but again, only at DC dealers. D.C. Code § 50-505 says a DC dealer must give you written notice of any known material mechanical defect, and of fire, water, or collision damage where repairs cost more than $1,000. Your protection on the Maryland side is different: Maryland requires a used car to pass a state safety inspection before it can be titled and registered. Either way, still pay your own mechanic to look at the car. Paper is not a substitute for eyes.
The Path Forward
Don't let the despair win, and don't let the border fool you. Save your down payment, try DC Credit Union first, then walk the Maryland corridors with your pay stubs in hand. The approval was ten minutes past the District line, waiting on your paycheck.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
A lot of DC cars sleep on the street or in an open apartment lot, blocks from your door. This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day and lights up when anyone walks up at night — no wiring, no electrician, no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Recommended · Temu
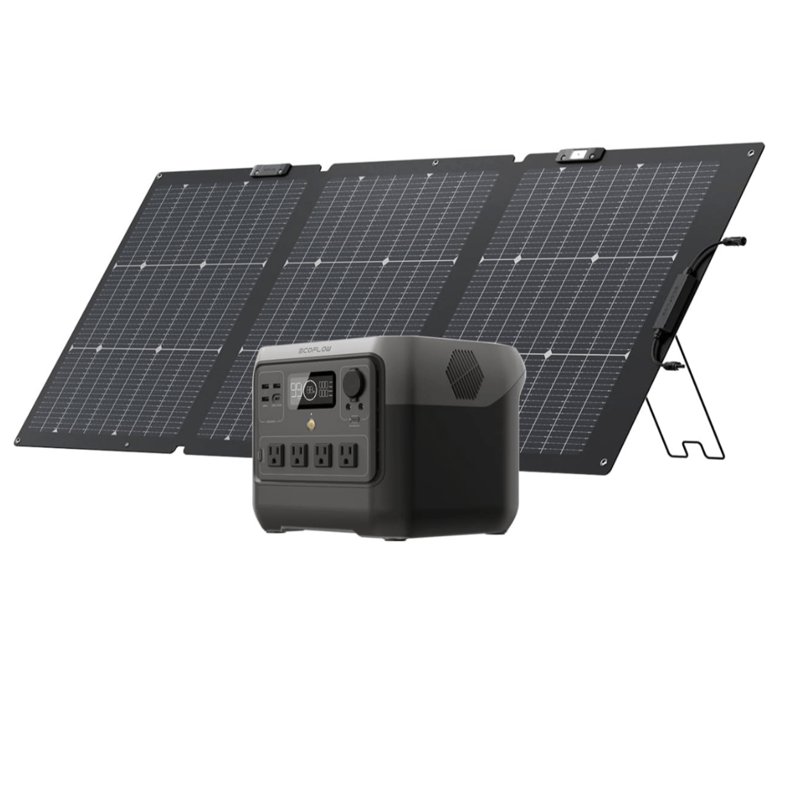
EcoFlow RIVER 2 Pro 700 Portable Power Station (716Wh LiFePO4, 800W AC)
The bigger backup: 716Wh and 800W of AC — enough for a fridge, a TV, or a work laptop through a long outage. Recharges in about 70 minutes. Silent, no fumes, safe indoors.
$327.16 on Temu
See the EcoFlow Pro on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can I get a car loan in Washington DC with a 500 credit score?
Yes. The buy here pay here lots in Suitland, Temple Hills, and District Heights approve on income and down payment, not score. A 500 score doesn't disqualify you — having no job or no cash down does.
Why are most of the bad-credit lots outside DC?
Rent and lot space. In-house financing lots need big, cheap lots, and those are in Prince George's County, Maryland — along Saint Barnabas Road, Marlboro Pike, and Old Silver Hill Road, minutes from the DC line.
If I buy in Maryland but live in DC, where do I register the car?
In DC. A car housed and operated in the District must be registered with DC DMV, pass DC inspection, and carry DC insurance — no matter which state the lot was in.
Is there a limit on the interest a dealer can charge in DC?
For a retail installment contract under DC law, yes — D.C. Code § 50-602 caps the finance charge, topping out at 28.33% for the oldest used-car class. A contract signed at a Maryland lot falls under Maryland law instead, so ask which law governs your deal.