Can You Buy a Lamborghini With Bad Credit?
Quick answer: Almost certainly not right now — exotic lenders want 700+ credit scores, 20% down, and clean histories. But the door isn't locked forever: a massive down payment, a strong co-signer, or 12–18 months of credit repair can get you there.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Let's start with the truth nobody tells you
Here's the thing about a Lamborghini. The car is the cheap part.
A 2026 Urus SE starts around $262,000. The Temerario — the Huracán's replacement — starts around $360,000. The Revuelto, the V12 flagship, is over $600,000. Those are real sticker prices, before options, and Lamborghini buyers routinely add $50,000 to $100,000 in options.
But the purchase price is just the cover charge. Insurance on a Lamborghini runs $300 to $540 a month for full coverage, depending on the model. Maintenance isn't Toyota money either. The people who finance these cars aren't stretching — they're comfortable.
That's why exotic lenders are picky in a way regular car lenders aren't.
What exotic lenders actually require
Specialty lenders like Woodside Credit — the biggest name in exotic car financing — publish their guidelines openly. Here's what they want:
- Credit score of 700 or above for the best rates
- No charge-offs, late payments, or bankruptcies on your record
- About 10 years of credit history preferred
- 20% down payment as the standard
- Proof you can comfortably handle the payment
The old Lamborghini factory finance program required a 700+ score just to get in the door, with 10% down minimum. That tells you everything: the exotic world starts where prime credit starts.
With a 500 or 550 score, you're not getting past the application. It's not personal. A $300,000 loan to someone with a history of missed payments is a risk no exotic lender will take — the cars are too expensive and too hard to resell if things go wrong.
Recommended · Temu
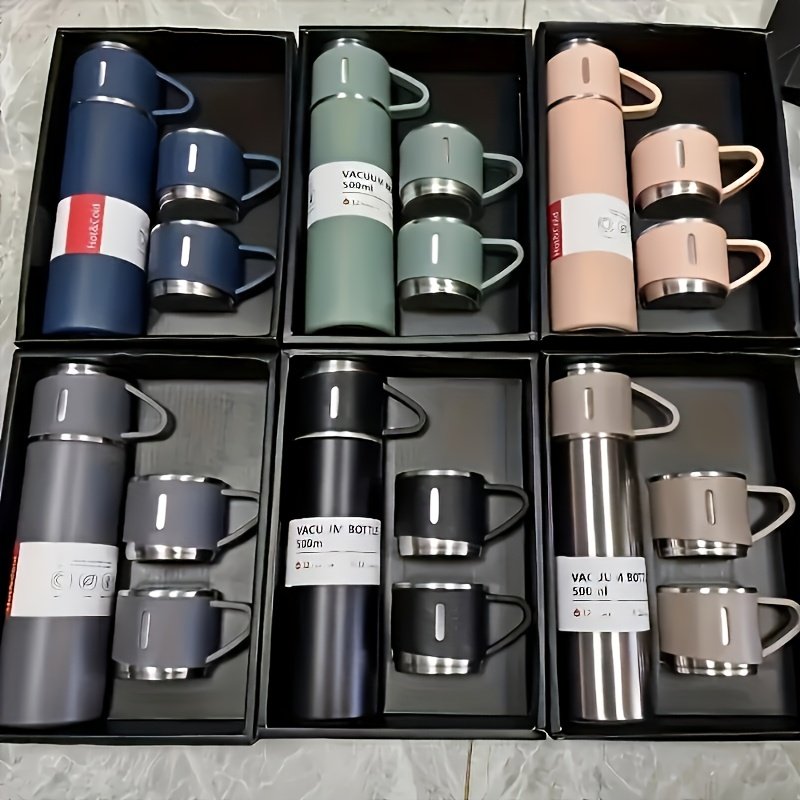
Insulated Cup Set — 4 Bottles & Cups, Gift Boxed
Coffee stays hot through a whole shift, and the set pays for itself in a week of skipped coffee runs. Four insulated bottles and cups, boxed up nice. 4.5 stars, 89K+ sold.
$5.18 on Temu
See the cup set on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The real math of a Lamborghini payment
Let's make this concrete. Take the "cheapest" Lamborghini, the Urus SE, at roughly $260,000.
Put 20% down ($52,000). Finance $208,000 for 72 months. With excellent credit at 6% APR, that's about $3,440 a month — before insurance, before gas, before maintenance.
Now run it with bad credit. If anyone would even approve you — and that's a big if — you'd be looking at double-digit APRs. At 15%, that same loan costs about $4,400 a month, and you'd pay over $100,000 in interest alone.
Add $300–$500 a month for insurance. You're looking at $5,000 a month to keep a Urus in your driveway with bad credit. That's a second mortgage in most of America.
The three real paths to a Lamborghini with bad credit
Path 1: Fix the credit first, buy the Lambo second. This is the honest answer and the one that actually works. Twelve to eighteen months of on-time payments, paying down balances, and disputing errors can take a 550 to a 700. The Lamborghini will still be there. And when you buy it with a 700+ score, you'll pay tens of thousands less in interest.
Path 2: Bring an enormous down payment. Money talks louder than credit scores. If you can put 40–50% down on a used Lamborghini — say $80,000 on a $160,000 used Huracán — some specialty lenders will listen even with imperfect credit, because their risk is cut in half. This is the "cash is king" path.
Path 3: A co-signer with excellent credit. If someone with a 750+ score and strong income co-signs, the lender underwrites them, not you. This is how most bad-credit exotic purchases actually happen — a business partner, a spouse, a parent.
What doesn't work: hoping a buy-here-pay-here lot has a Lamborghini out back. They don't. Exotic cars live in a completely different financing universe from the lots this site usually covers.

Recommended · Temu
V519 OBD2 Scanner — Check Engine Code Reader
Before you sign for that used car, plug this in under the dash and read the codes yourself. It shows check-engine codes and live data — the stuff a seller hopes you never check. 4.6 stars, 28K+ sold on Temu.
$17.01 on Temu
See the scanner on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Whether it's a Lamborghini or a Honda, the math is the same
Here's the part nobody expects on a Lamborghini article: the playbook is identical to buying any car with bad credit. It starts with the down payment. Every extra dollar you put down shrinks the loan, drops the payment, and makes the lender say yes faster — whether the car costs $12,000 or $360,000.
So dream about the Lamborghini. Seriously. But start climbing the actual ladder today:
- Figure out your real down payment number with the Bad Credit Down Payment Calculator — it adjusts to your credit score.
- Learn why the down payment matters more than your score in the down payment obstacle guide.
- See what rate your score actually gets you with the Car Loan Rates by Credit Score Calculator.
The Lamborghini will still be there when you're ready. The question is whether you'll be ready sooner because you started now.
The used Lamborghini shortcut
Here's something most people miss: you don't need a new one. A used Huracán or Gallardo runs $150,000 to $200,000 — still serious money, but roughly half the price of a new Temerario. The exotic lenders finance used cars too, and the same three paths above apply at much more reachable numbers.
A $160,000 used Huracán with 30% down ($48,000) and a 700 score is a fundamentally different proposition than a $360,000 new Temerario with bad credit and $10,000 down. Same badge. Same roar. Half the mountain to climb.
What about buying a Porsche, Ferrari, or McLaren with bad credit?
Whether you're looking to buy a Porsche with bad credit, a Ferrari with bad credit, or a McLaren with bad credit, the playbook is the same — only the price tags change. A Porsche 911 Carrera starts around $130,000, a Ferrari 296 GTB around $350,000, a McLaren Artura around $240,000. Every exotic lender applies the same standards no matter the badge: strong credit (700+), 20 to 30% down, clean history.
The one real difference: Porsche is the easiest exotic to finance with imperfect credit, because Porsche Financial Services is a captive lender (like Toyota Financial, but for sports cars) and occasionally more flexible than the independent exotic specialists. Ferrari and McLaren buyers almost always go through third-party exotic lenders like Woodside Credit or Premier Financial Services, which hold the line at 700+.
So if your heart is set on an exotic but your credit isn't there yet, a used Porsche 911 is the most reachable entry point — same three paths above, lower mountain. And the supercar financing calculator above runs the numbers for all of them.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Dreaming big? Protect the dream. These solar security lights (3000LM, motion sensor, 3 heads) guard your driveway for under $20 — no wiring, no electrician.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
20,000mAh Solar Power Bank — Charges in the Sun
Your phone is your job — the lender's call, the gig app, the map. This 20,000mAh bank tops up from the sun and keeps your phone alive all shift. 4.7 stars.
$4.98 on Temu
See the power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can you finance a Lamborghini with a 600 credit score?
Not through exotic specialty lenders — they want 700+. Your realistic options are a very large down payment (40%+), a strong co-signer, or repairing your credit into the 700s first.
How much down payment do you need for a Lamborghini?
20% is the standard expectation from exotic lenders — that's $52,000 on a Urus SE, $72,000 on a Temerario, $120,000+ on a Revuelto. With weaker credit, expect lenders to demand 30–50%.
What is the monthly payment on a $300,000 Lamborghini?
With 20% down and good credit at 6% APR over 72 months, roughly $3,900 a month before insurance. With bad credit — if approved at all — the same car could cost $5,000+ a month.
What credit score do you need to buy a Lamborghini?
700 minimum for specialty exotic lenders like Woodside Credit, 740+ for the best terms. Below 700, you'll need a co-signer, a huge down payment, or time to rebuild first.
Can you buy a Ferrari or Porsche with bad credit?
Same rules as Lamborghini — exotic lenders want 700+ and 20-30% down regardless of the badge. Porsche is the slightly easier path since Porsche Financial Services is a captive lender and can be more flexible than independent exotic specialists. A used 911 is the most reachable exotic entry point.
Trademark notice: This site is not affiliated with, sponsored, or endorsed by Lamborghini, Ferrari, Porsche, or McLaren. All trademarks are the property of their respective owners.