Low Down Payment Cars in Nashville
Quick answer: In Nashville, $500 down is real — but it buys you the oldest cars on Nolensville Pike and Dickerson Pike, not the one in the ad photo. And $500 down is not $500 to drive off: tax, title, and registration come on top. Here's what that money actually does at a Nashville lot.
Recommended · Temu
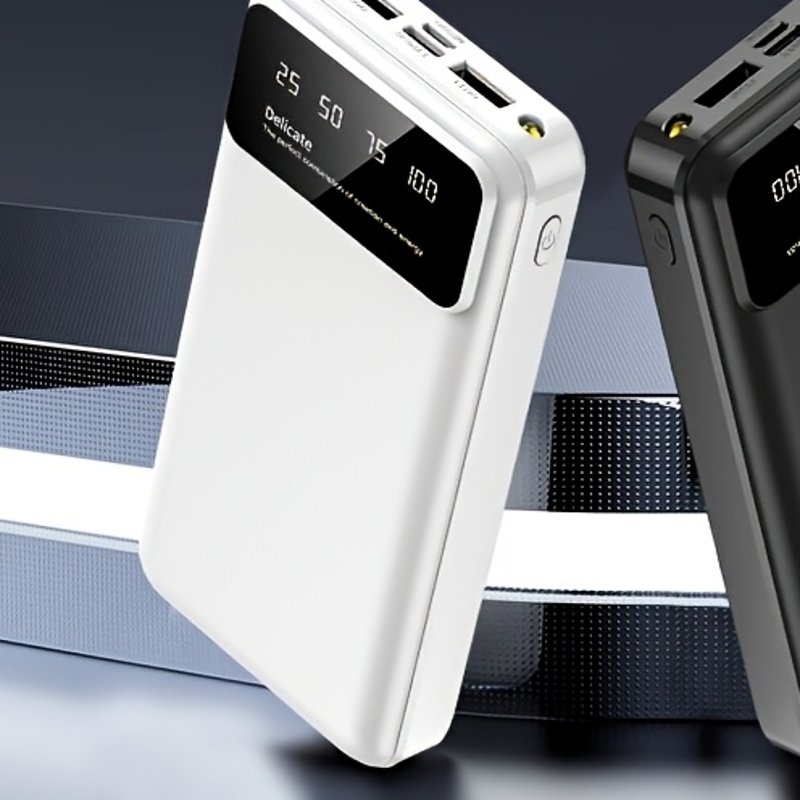
50,000mAh Power Bank — Big Phone Backup Battery
One big battery to keep the family's phones charged through a blackout, a road trip, or a long week away from an outlet. Plain and simple: 50,000mAh. 4.7 stars.
$11.58 on Temu
See the big power bank on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
Every bad-credit buyer I know hits the same wall. It's not the score. It's not the job. It's the down payment — cash, in hand, today. The obstacle is always the down payment, and the lots know it, which is why "$500 down" is painted bigger than the price of the car.
Here's the blunt truth about that $500: it doesn't buy the car. It buys your approval. The lot uses it to cover its risk so it can say yes to a buyer a bank wouldn't touch. That's not a scam — it's the deal. But go in thinking $500 is the whole cost of getting on the road and you'll get hurt. It isn't. It never is.
What $500 Down Really Buys on the Pikes
Let's talk about the actual Nashville market. Auto Mart on Nolensville Pike — in-house financing since 1963 — lists its cars at roughly $6,995 to $14,995. The lots on Dickerson Pike, Gallatin Pike, and Charlotte Pike work the same price neighborhood: older sedans, small SUVs, and work trucks, most of them 8 to 15 years old.
On the cheapest cars in that range, $500 down is a real number. The lot can make the deal work because the car is cheap and the payments come fast — weekly or biweekly. On a $12,000 car, $500 down is a fantasy the ad hopes you won't test. The down payment follows the car: expect roughly 10% or more of the price on anything decent, which is why the honest planning number for most Nashville buyers is $500 to $1,000.
And here's what $500 down does to your payment. Finance $6,500 on a short in-house term and the weekly number gets big, fast. A smaller down payment doesn't save you money. It moves the money into the payment column, where it collects finance charges on the way.
Recommended · Temu
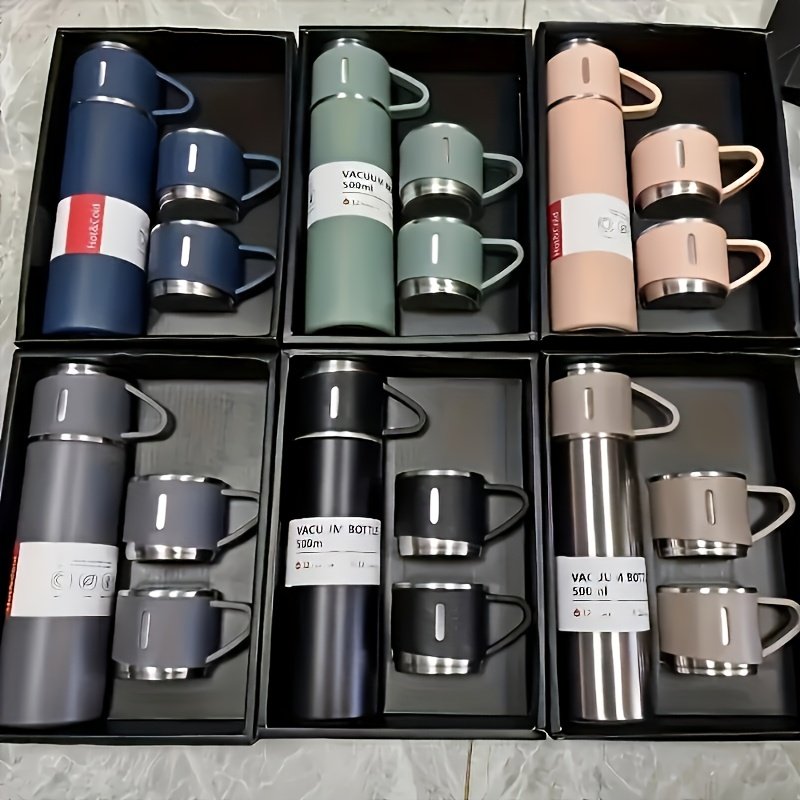
Insulated Cup Set — 4 Bottles & Cups, Gift Boxed
Coffee stays hot through a whole shift, and the set pays for itself in a week of skipped coffee runs. Four insulated bottles and cups, boxed up nice. 4.5 stars, 89K+ sold.
$5.18 on Temu
See the cup set on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Down Payment Is Not Drive-Off Money
This is the mistake that empties wallets at the lot. Three different numbers get called "down":
The down payment is what goes against the price of the car.
The drive-off amount is every dollar you hand over before the keys: down payment plus tax, title, and registration fees, plus the first insurance payment. In Tennessee that tax-and-fees stack is real money on top of the price, and nobody puts it on the windshield sign.
A deferred down payment — sometimes called a pick-up payment — is when the lot lets you pay part of the down later, usually out of your next paychecks. It feels like help. Read it carefully: if you miss that pick-up payment, some contracts treat it as a default from day one.
Before you visit any lot on Nolensville or Dickerson Pike, ask one question on the phone: "What is the total cash I need to drive off today?" If they won't answer it straight, that's your answer about the lot.
How to Grow $500 Into $1,000 Fast
If $500 is where you are and $1,000 is where the better cars start, don't despair — close the gap like it's a job, because it pays like one.
Sell what you don't use. Tools, a second phone, the gaming system, the rims in the garage. Nashville's resale apps move fast. Two hundred dollars of sold clutter is two hundred dollars of down payment that doesn't collect interest.
Take the tax refund seriously. If a refund is coming, it is a down payment with your name on it. Tax season is when the pikes do their biggest business for a reason. Planning to buy in February with a refund beats financing in October with nothing.
Save on a schedule, not a hope. Fifty dollars a week is $500 in ten weeks. Set it aside the day you're paid, before it can leak. And bring a trade if you have one — even a rough runner with a clean title counts as down payment money at most in-house lots.
Buy the cheaper car on purpose. The fastest way to need less down is to need less car. The $7,000 sedan you can afford beats the $13,000 SUV that eats your whole check.

Recommended · Temu
1080P Video Doorbell Camera — Wireless, No Drilling
Your car sleeps in the apartment lot. This camera sticks on with no drilling, runs on a battery, and shows your front door — and who is near your car — right on your phone. 4.7 stars, 250K+ sold.
$9.98 on Temu
See the doorbell on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The Total-Cost Math Nobody Shows You
Run this before you sign. A $7,000 car with $500 down leaves $6,500 financed. Tennessee law caps the dealer's finance charge on a retail installment contract — the time price differential — at $11.75 per $100 per year on the amount financed (Tenn. Code § 47-11-103). On a three-year deal that's up to roughly $2,300 of finance charge stacked on top, before fees. Your $7,000 car can cost $9,800 by the last payment.
Now put $1,500 down instead. You finance $5,500. The finance charge shrinks, the payment shrinks, and the lot's risk shrinks — which is exactly why bigger downs get faster yeses and better cars. Every extra dollar down is a dollar that never pays interest. That's the whole game.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
When every dollar went to the down payment, protecting the car cheaply matters — Nashville's apartment lots and street parking off Charlotte Pike stay dark. This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day, needs no wiring or electrician, and guards your driveway without adding a dime to the electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
Can I really get a car in Nashville with $500 down and bad credit?
Yes, at in-house financing lots on Nolensville Pike, Dickerson Pike, and Gallatin Pike — but $500 down pairs with the cheapest cars on the lot, typically the $6,000–$8,000 range, and you'll still owe tax, title, and fees on top.
What else do I have to pay besides the down payment in Tennessee?
Tax, title, and registration fees, plus insurance before you drive off. Ask the lot for the total drive-off number — down payment plus everything else — before you go in.
Does a bigger down payment lower my payment in Nashville?
Yes, twice over: you finance less, and you pay finance charges on less. It also makes approval easier, because the lot's risk drops. On in-house deals, the down payment is the strongest negotiating tool you have.
What if a Nashville lot offers me a deferred down payment?
It means part of your down is due later, usually within a few paychecks. Get the dates and amounts in writing, and ask what happens if you miss one — on some contracts, missing a deferred down payment is a default that can trigger repossession.