Car Loan After Repossession in Memphis
Quick answer: Yes, you can get a car loan in Memphis after a repossession — the in-house lots on Covington Pike and Elmore Road approve post-repo buyers every day. But Tennessee law is not gentle: there's no warning before a repo, no guaranteed right to catch up, and you can still owe money after the car is sold. Know the rules before you sign your comeback deal.

Recommended · Temu
6x4 Ft Brown Outdoor Storage Shed with Lockable Double Doors
Just bought the car? Clear the garage so it actually fits. This weatherproof steel shed has lockable double doors — and no monthly storage-unit bill.
$137.21 on Temu
See the shed on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Mike's take
A repo feels like the end of the story. You walk out in the morning, the car is gone, and the warehouse shift still starts at six. In Memphis, where the job is almost always a drive away, that morning is despair in its purest form.
Here's the blunt truth, and then the hope. The truth: Tennessee is one of the harder states to have a repo in — the law gives the lender most of the power, and gives it fast. The hope: Memphis might be the easiest city in the state to come back in, because the Covington Pike market runs on buyers exactly like you — income, down payment, and a past they're not interested in judging. What a repo changes is the price you'll pay. So this time, you go in knowing exactly what the law says.
What Tennessee Law Actually Says About Your Repo
Forget what you've heard from friends in other states. This is Tennessee, verified from the statutes:
No warning before the tow. Under Tenn. Code § 47-9-609, a lender can repossess after default without court and without telling you first, as long as the repo doesn't breach the peace. There's no grace period in the statute — your contract sets the terms.
No guaranteed right to cure. Some states force lenders to give you a window to catch up and stop the repo. Tennessee does not. If your contract includes a cure clause, the lender must honor it — but the law itself doesn't give you one.
You do get notice before the sale. The lender must send you a notice of disposition before it sells the car (Tenn. Code § 47-9-611). A notice sent at least 10 days before the sale counts as timely under § 47-9-612, and in a consumer deal it must state what you'd owe if the sale falls short and give you a phone number for the exact payoff to get the car back (§ 47-9-614). Watch your mailbox — that notice is your clock.
Getting the car back means paying it all off. Redemption under § 47-9-623 means the full remaining balance plus the lender's reasonable repo expenses — not just the payments you missed. For most people that number is out of reach, which is why the smarter fight is usually the next paragraph.
You can still owe money after the sale. If the car sells for less than you owed, you owe the difference — the deficiency (§ 47-9-615). But you have a real defense: if you challenge it, the lender must prove the sale was commercially reasonable — proper notice, proper sale, fair process. If it can't, § 47-9-626 presumes the car was worth the full debt, which can wipe the deficiency out. A botched notice isn't a technicality in Tennessee; it's money. And if the lender broke the disposition rules on a consumer deal, § 47-9-625 sets minimum damages of the finance charge plus 10% of the principal.
One more detail: after a vehicle repo, the lender must notify the county sheriff under Tenn. Code § 55-5-128. If you come home to a missing car, a call to the Shelby County Sheriff can tell you whether it was a repo or a theft.
Recommended · Temu
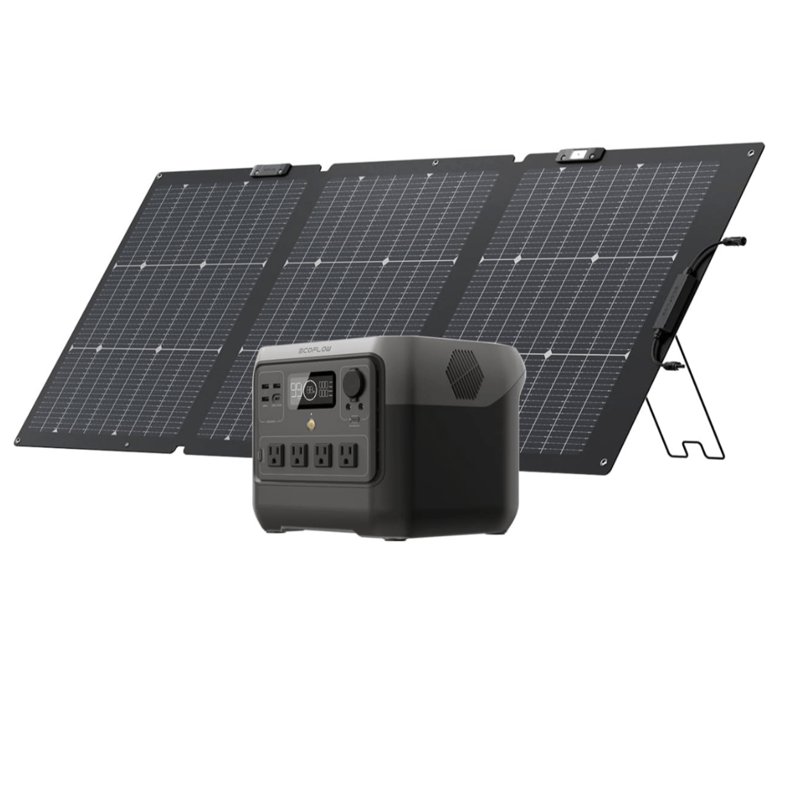
EcoFlow RIVER 2 Pro 700 Portable Power Station (716Wh LiFePO4, 800W AC)
The bigger backup: 716Wh and 800W of AC — enough for a fridge, a TV, or a work laptop through a long outage. Recharges in about 70 minutes. Silent, no fumes, safe indoors.
$327.16 on Temu
See the EcoFlow Pro on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
How Long Should You Wait?
There's no state-mandated waiting period. The timeline is practical, not legal.
Most Memphis in-house lots will talk to you almost immediately — a repo is last month's news to a dealer who is the bank, and some corridor ads advertise approvals for buyers with repossessions outright. Bigger subprime lenders usually want 12 months of clean history after a repo, and a credit union like Orion Federal Credit Union will want the repo older and your record rebuilt. The ladder: lot financing now if you must drive, subprime lender in a year, credit union after that.
What you do while you wait matters more than the wait. Save the down payment — a post-repo buyer with $1,500 down is a different risk than one with $200. And if a deficiency from the old car hangs over you, deal with it directly: respond to any lawsuit, and use the commercially-reasonable-sale defense if their paperwork was sloppy.
Who Approves Post-Repo Buyers in Memphis
The Covington Pike corridor is your first stop. Triumph Auto Sales on Elmore Road advertises guaranteed credit approval for good, bad, or no credit. Rogers Used Cars, also on Elmore, advertises guaranteed financing. Corridor ads go further, pitching buyers with repossessions by name — "when they say no, we say yes" is the genre. DriveTime finances buyers rebuilding after credit damage as its core business.
Ask every one of them three questions: Do you report to the bureaus? What's the total of payments, in writing? And what does your contract give me if I fall behind — any grace period, any cure window? In Tennessee, whatever they promise has to live in that contract, because the statute won't supply it later.
And don't confuse a fresh start with a title loan. Tennessee title pledge loans are a different product entirely — capped at $2,500, written in 30-day terms, at 2% interest per month plus a fee of up to a fifth of the loan. That's a trap with a state license, not a car loan.

Recommended · Temu
Portable Tire Inflator — Cordless Air Pump (150 PSI)
A flat tire on the way to work can cost you the job that pays for the car. This cordless inflator rides in the trunk and fills a tire in minutes — no gas-station air pump, no tow truck. 4.8 stars, 35K+ sold.
$7.45 on Temu
See the inflator on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
The Rebuilding Path
Your second chance works if you treat it as a bridge, not a home. Buy less car than they'll approve. Pay on time at a lot that reports — some corridor ads promise bureau reporting, so shop for it. Keep every receipt; Tennessee retail installment law entitles you to a written statement of your payments. In 12 to 18 months, refinance or trade up. The repo stays on your report for years, but a fresh string of on-time payments is the story lenders read first.

Recommended · Temu
2-Pack 3-Head Solar Security Lights (3000LM, Motion Sensor)
Your comeback car deserves watching over — especially parked in a Memphis apartment lot or on the street where the last one sat. This 2-pack of solar security lights (3000LM, motion sensor, 3 heads) charges by day, installs with no wiring and no electrician, and lights up anyone approaching your car, with no electric bill.
$22.26 on Temu
See the solar lights on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Recommended · Temu
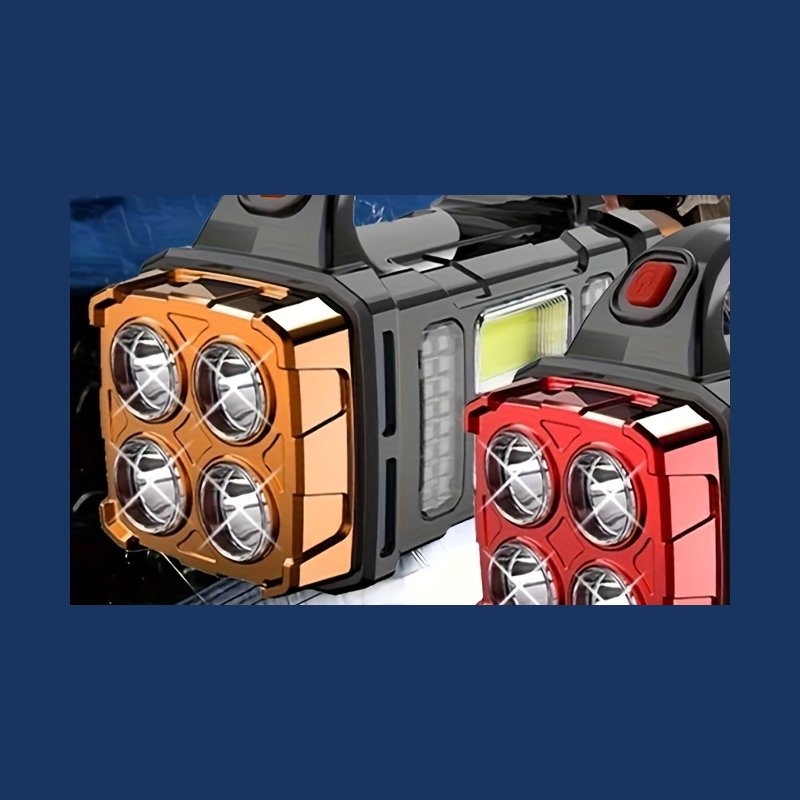
Solar & USB LED Lantern — COB Work Light
When the power goes out, this is your light. It charges from the sun or any USB port — no candles, no wiring, nothing to install. 4.7 stars, 100K+ sold.
$4.94 on Temu
See the lantern on TemuAffiliate link: if you buy, this site may earn a commission at no extra cost to you. Price checked September 2026; Temu prices change often.
Frequently asked questions
How soon after a repossession can I get a car loan in Memphis?
There's no legal waiting period. In-house lots on Covington Pike and Elmore Road may approve you within weeks if you have income and a down payment. Subprime lenders typically want about a year of clean history; credit unions want more.
Does Tennessee give me a right to catch up payments before a repo?
No. Tennessee law does not guarantee a right to cure. A lender can repossess after default with no advance notice under Tenn. Code § 47-9-609, as long as it doesn't breach the peace. Any cure window must come from your contract.
Can I still owe money after my car is repossessed and sold in Tennessee?
Yes — if the sale brings less than you owed, you owe the deficiency under § 47-9-615. But if the lender can't prove the sale was commercially reasonable, including proper notice under §§ 47-9-611 and 47-9-614, § 47-9-626 can reduce or eliminate it.
Can I get my car back after a repossession in Memphis?
Yes, but only before it's sold, and only by redeeming it: the full remaining balance plus repo expenses under § 47-9-623 — not just the missed payments. Your notice of disposition must include a phone number for that exact payoff.